Predictive Reserving Analytics
Go Beyond Traditional Actuarial Models
Enhance your reserving and risk modeling process by properly capturing
calendar period effects and producing the full predictive distribution
Enhance your reserving and risk modeling process by properly capturing
calendar period effects and producing the full predictive distribution
BASR is modern stochastic actuarial software that models loss development triangles in all three dimensions, accident, development, and calendar period, using customizable statistical frameworks.
It supplements your traditional reserving process, quantifying the uncertainty around estimates and producing a full, statistically justified predictive distribution. Its point estimate can be used as an additional method or a priori, and its aggregate distributions reflect diversification benefits across multiple lines of business or segments.
Traditional actuarial reserving methods capture only the accident and development period dimensions, and their primary assumptions are violated under changing calendar period effects. With the pandemic heavily skewing (at least) two calendar period diagonals and social inflation running rampant in many P&C lines of business, these effects are the new normal, so it is more critical than ever to properly model and project them in our actuarial estimates. That is where BASR comes in, providing insights into the trends overlooked by traditional methods and producing estimates built on fully customizable future trend assumptions.
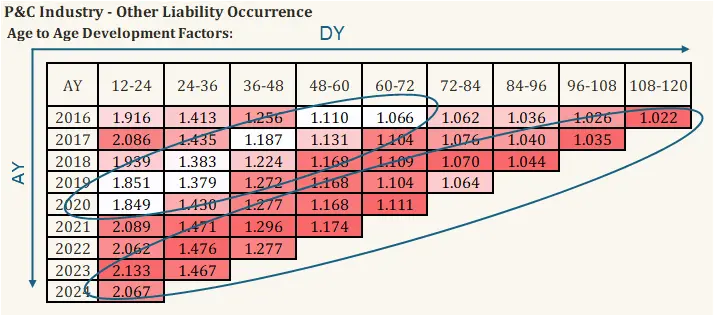
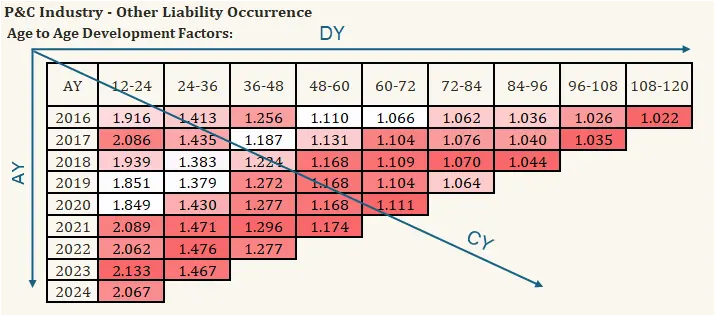
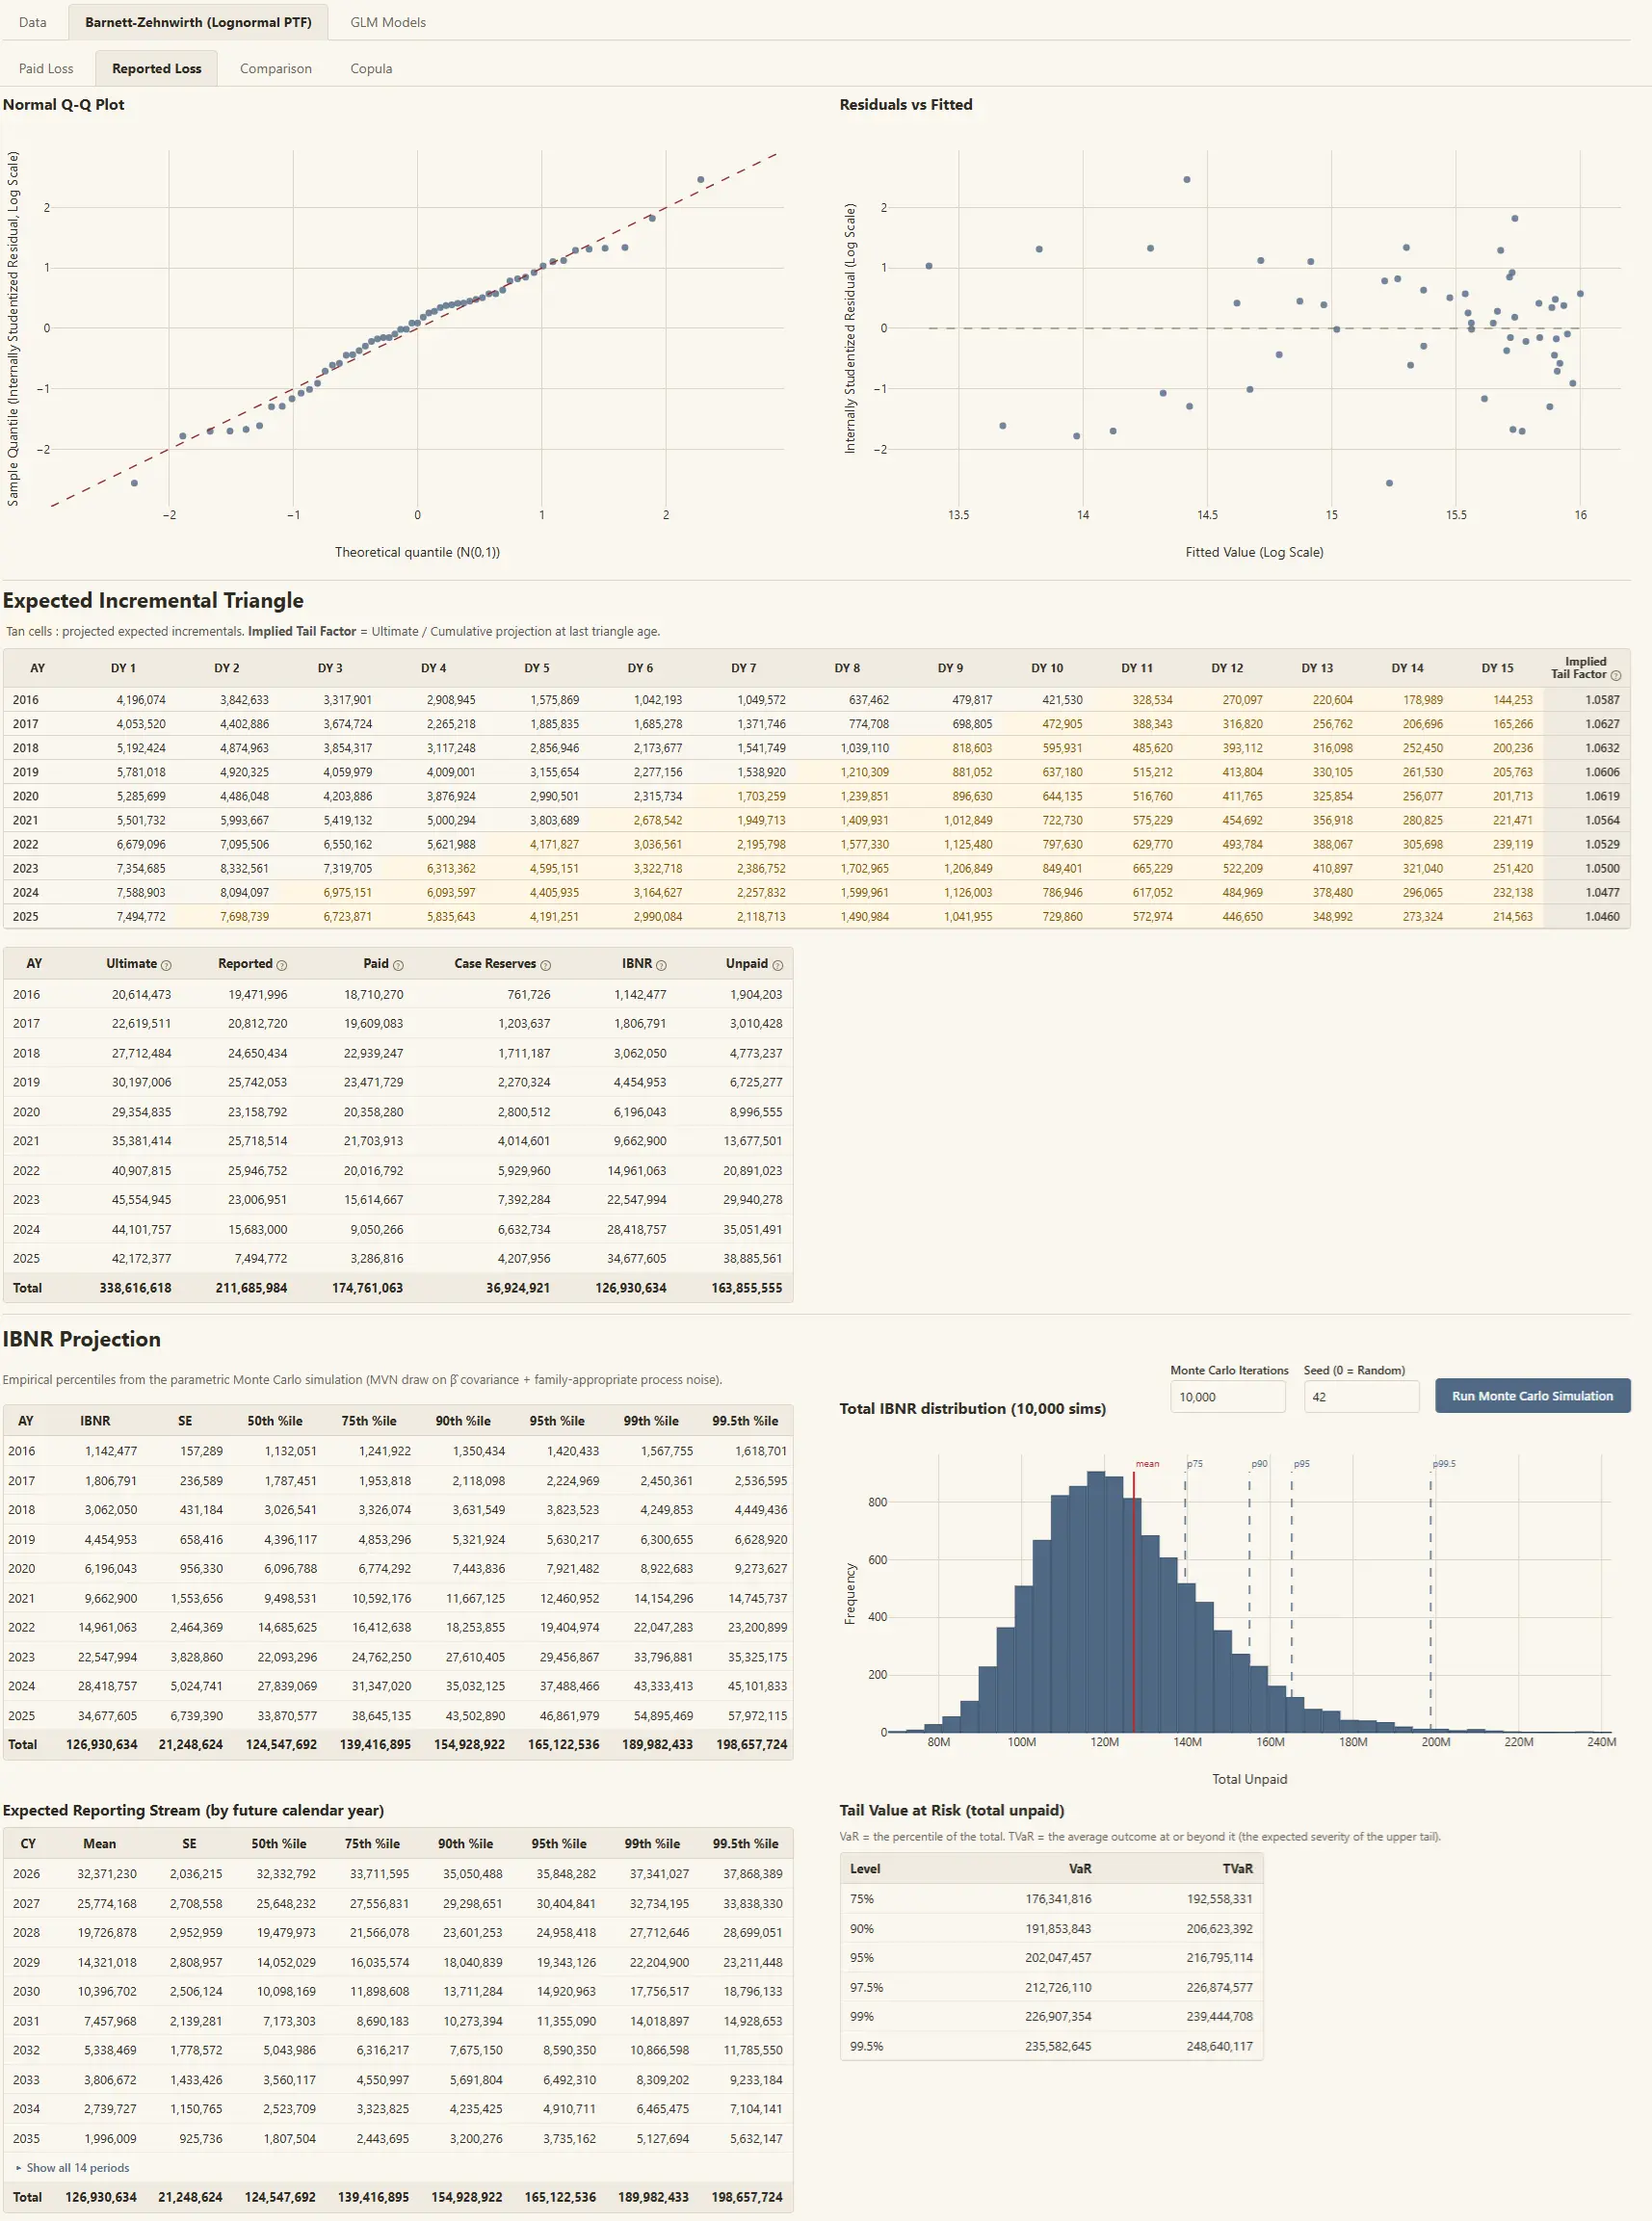
BASR includes an automated wizard that selects parameters based on the criterion of your choice (BIC, AICc, or likelihood ratio testing), giving a statistically principled reference point that can be refined by the actuary to incorporate knowledge of the underlying business and exposures. Statistical diagnostics of the model fit in all three directions (and overall) let the actuary quantify reserve uncertainty and form a narrative around observed trends, selections, and early warnings, not just provide a single number.
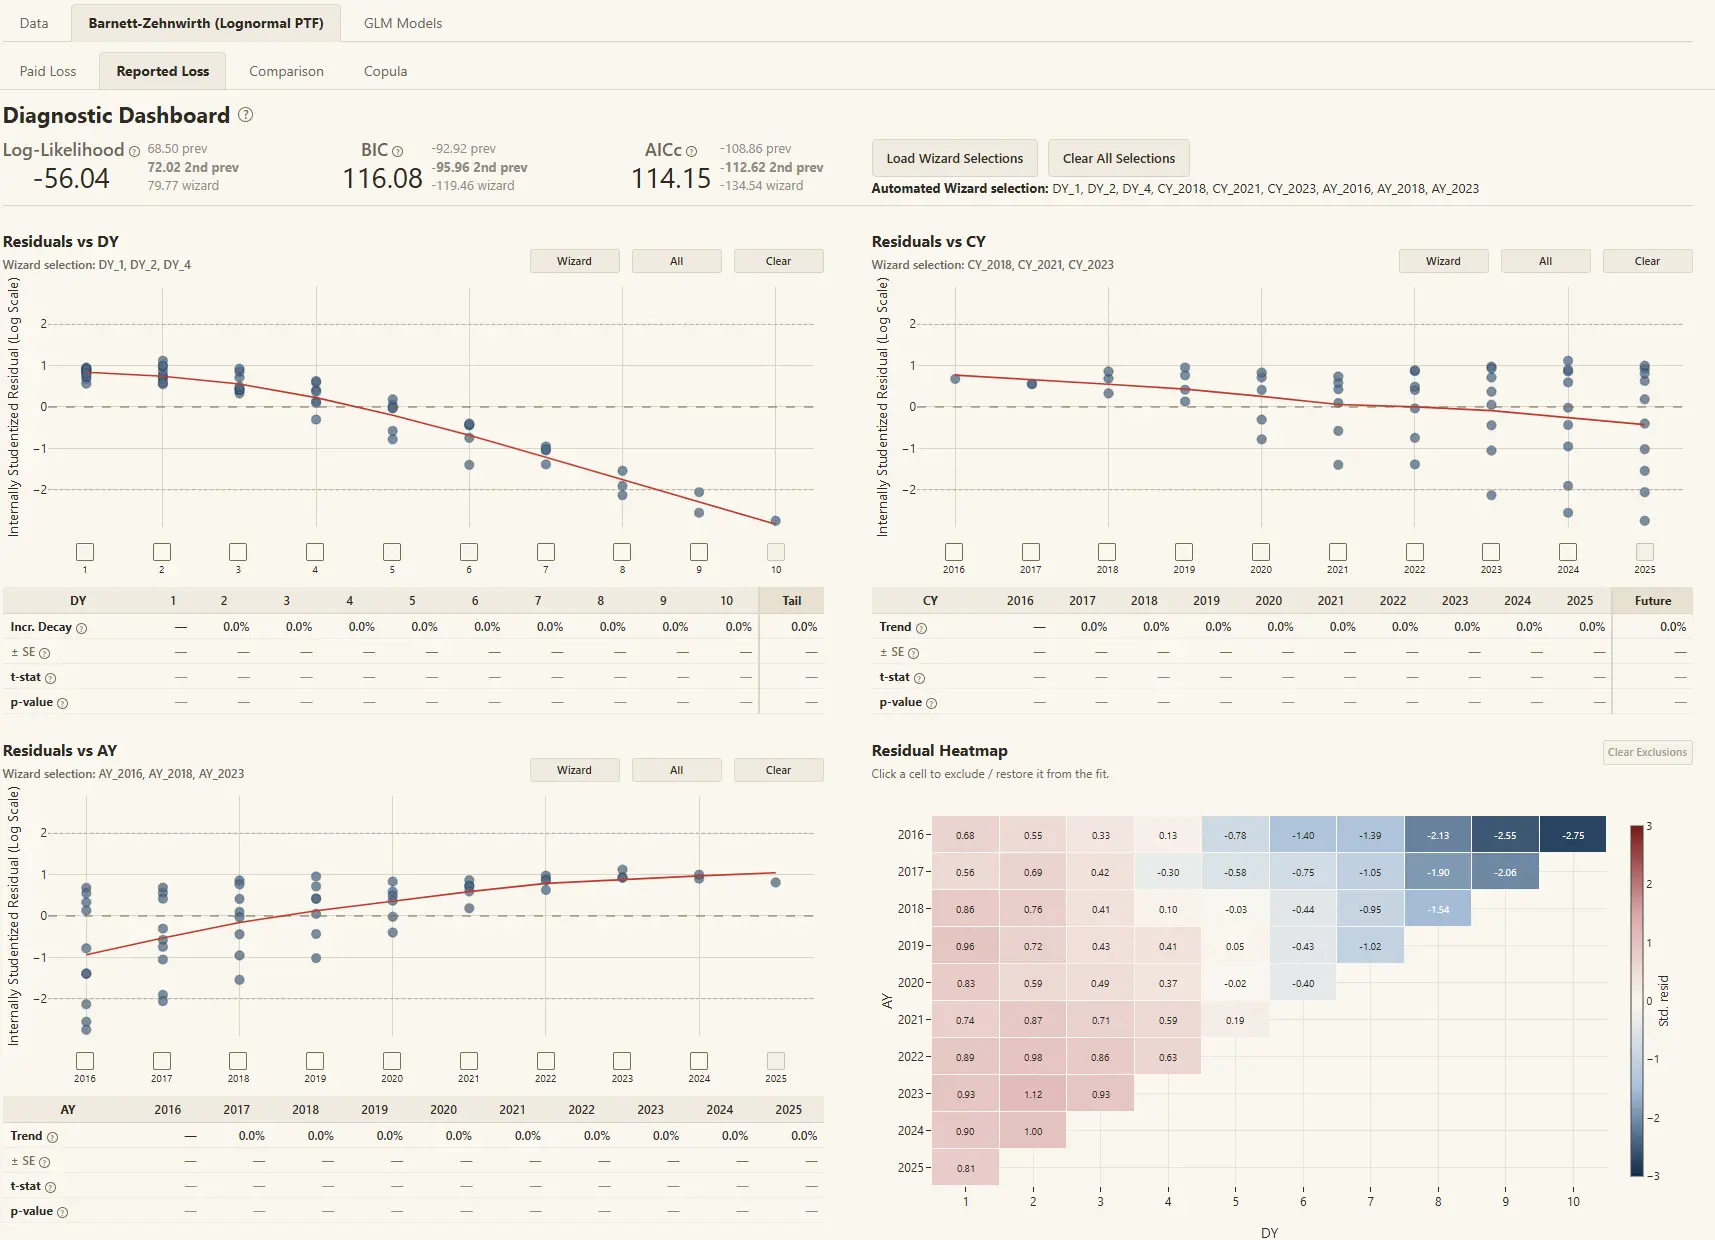
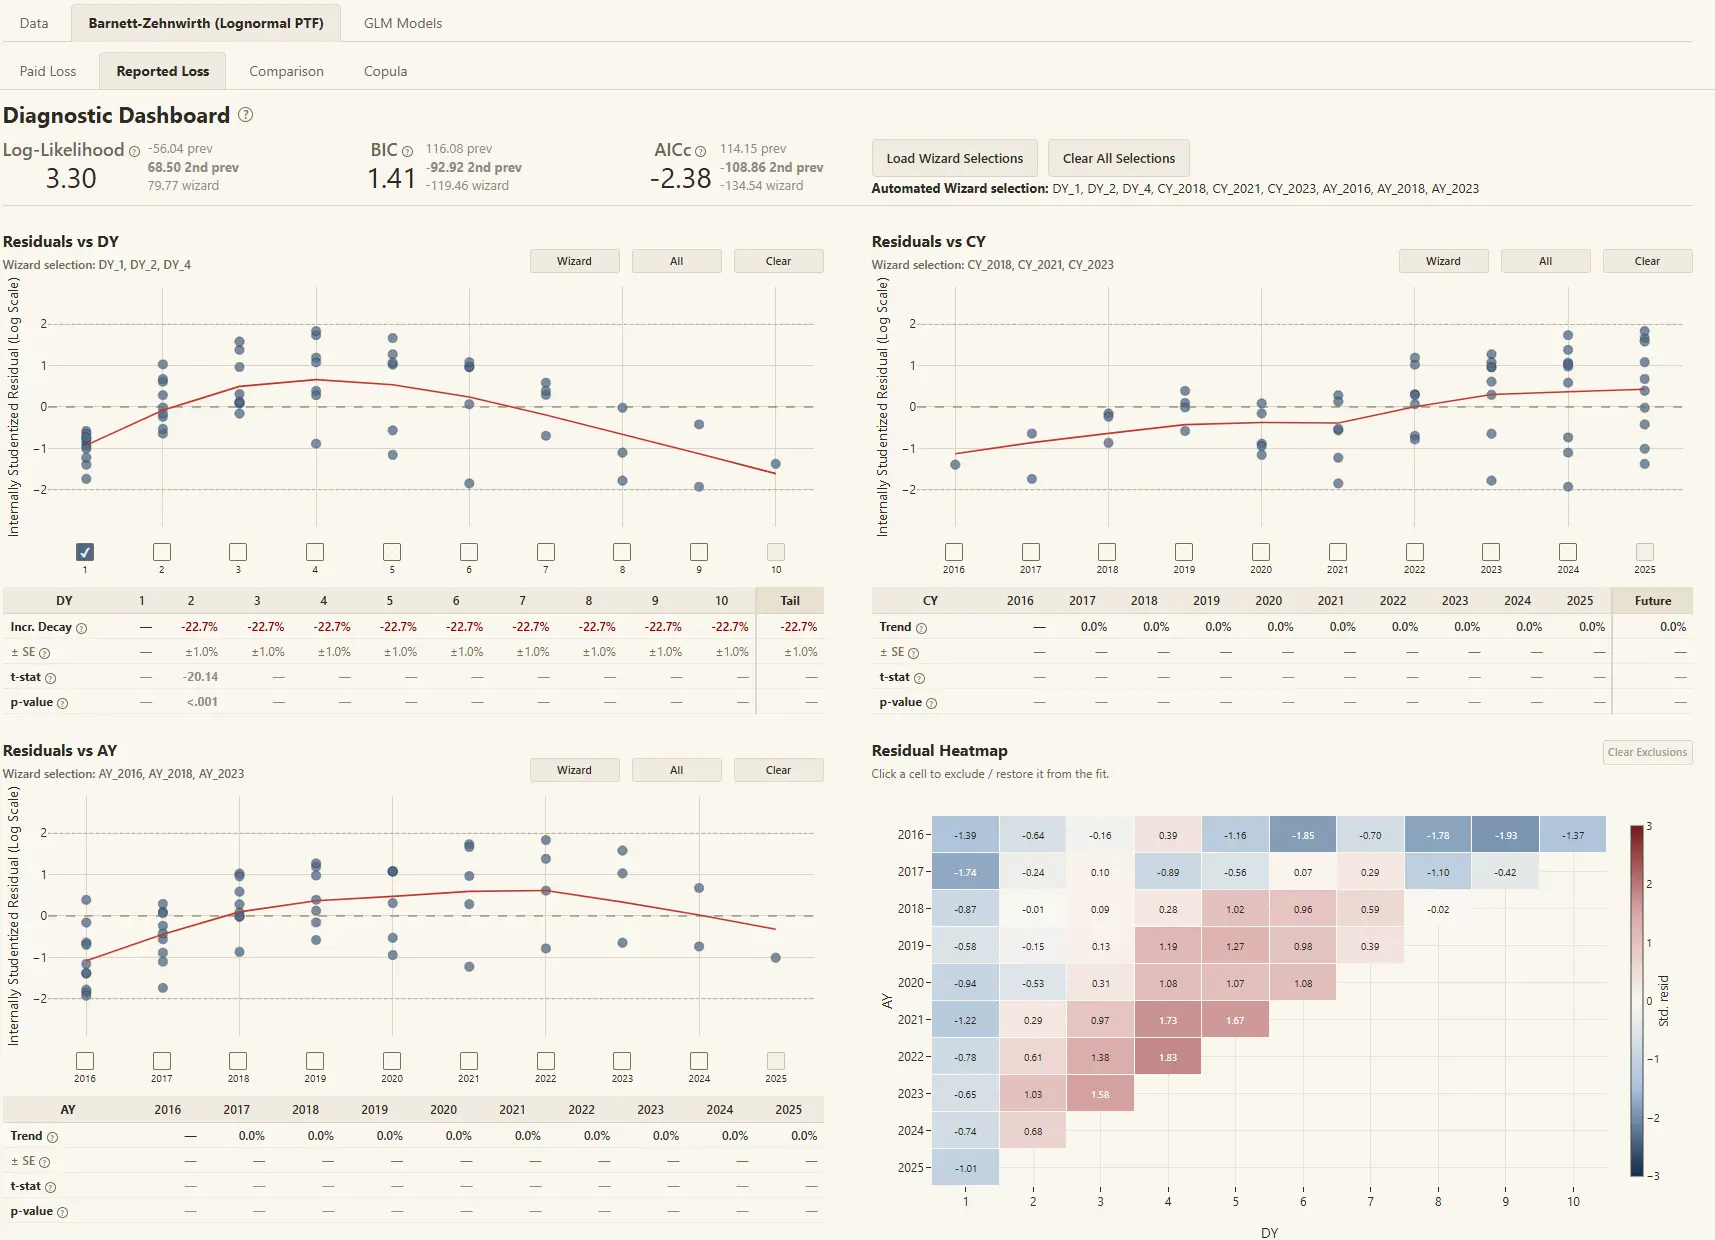
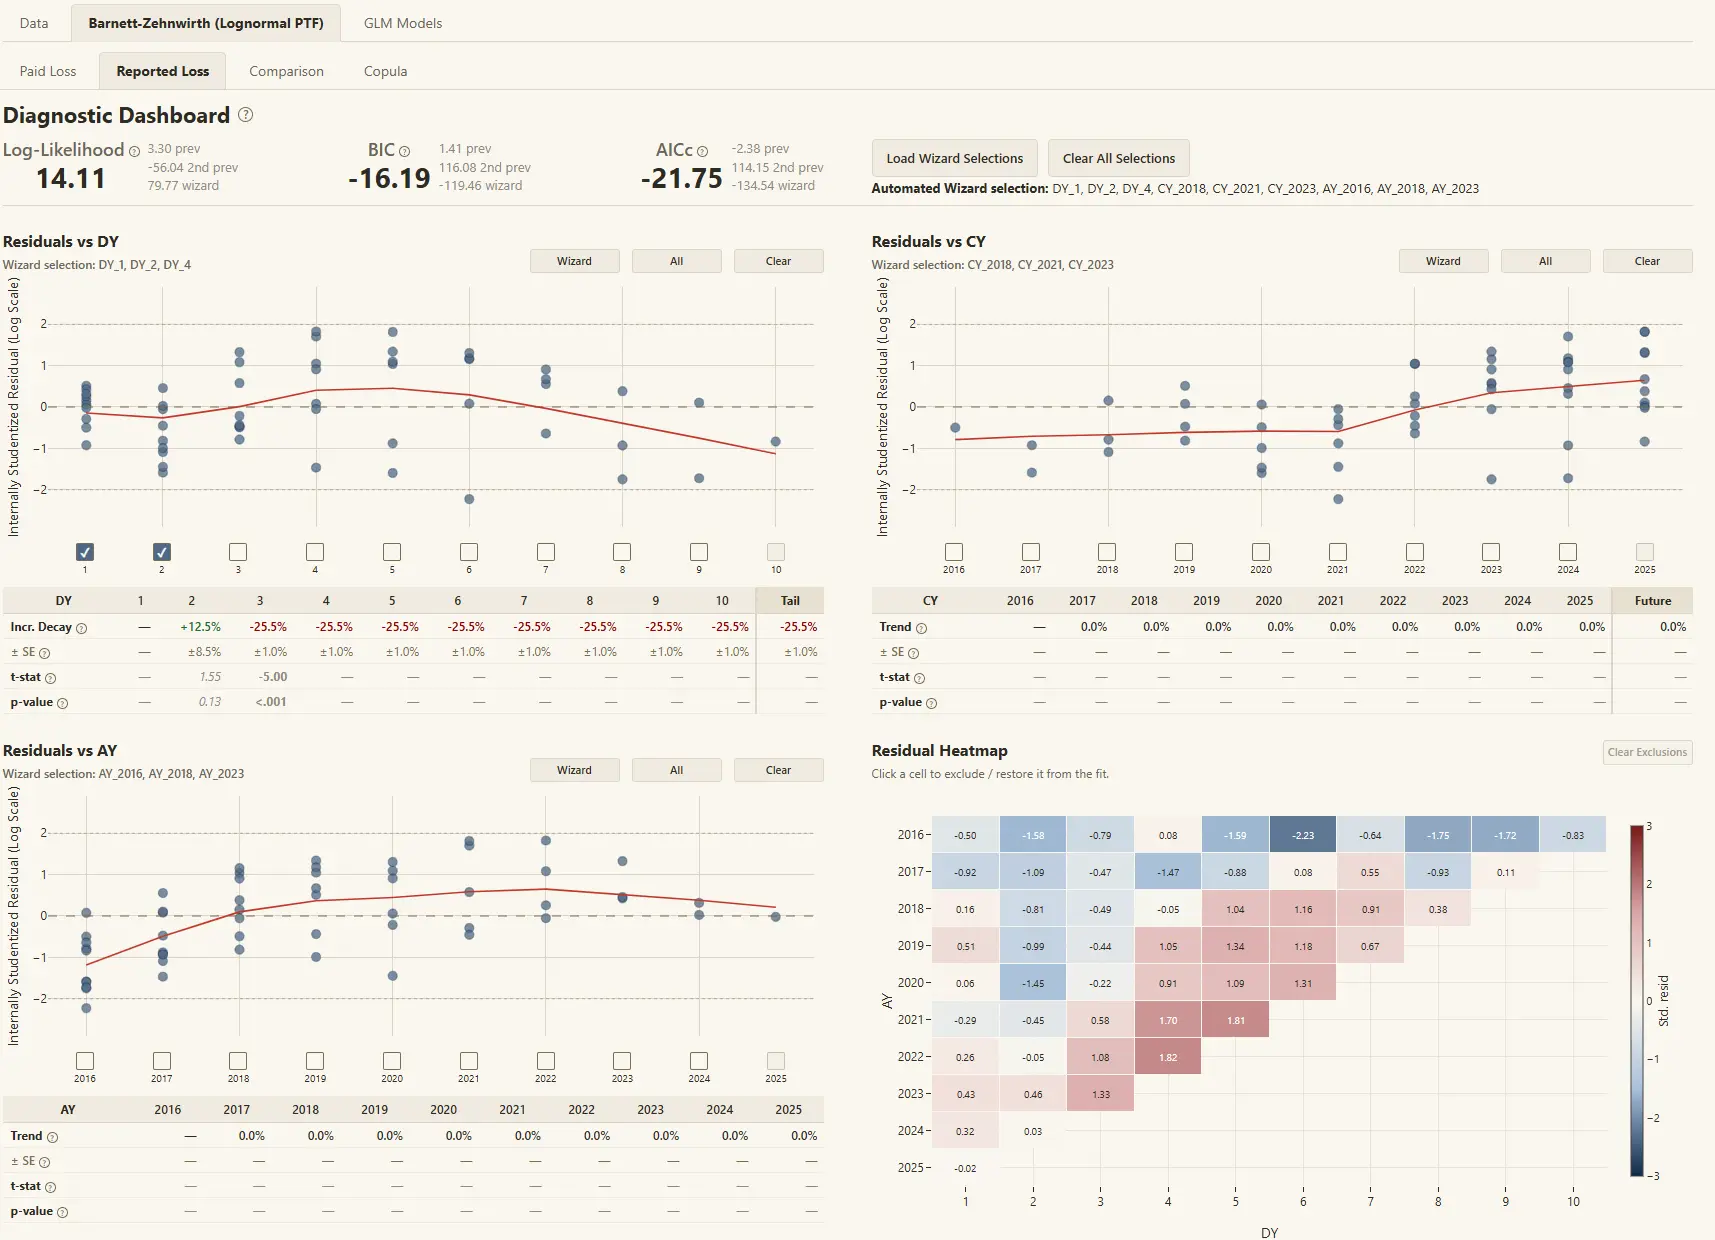
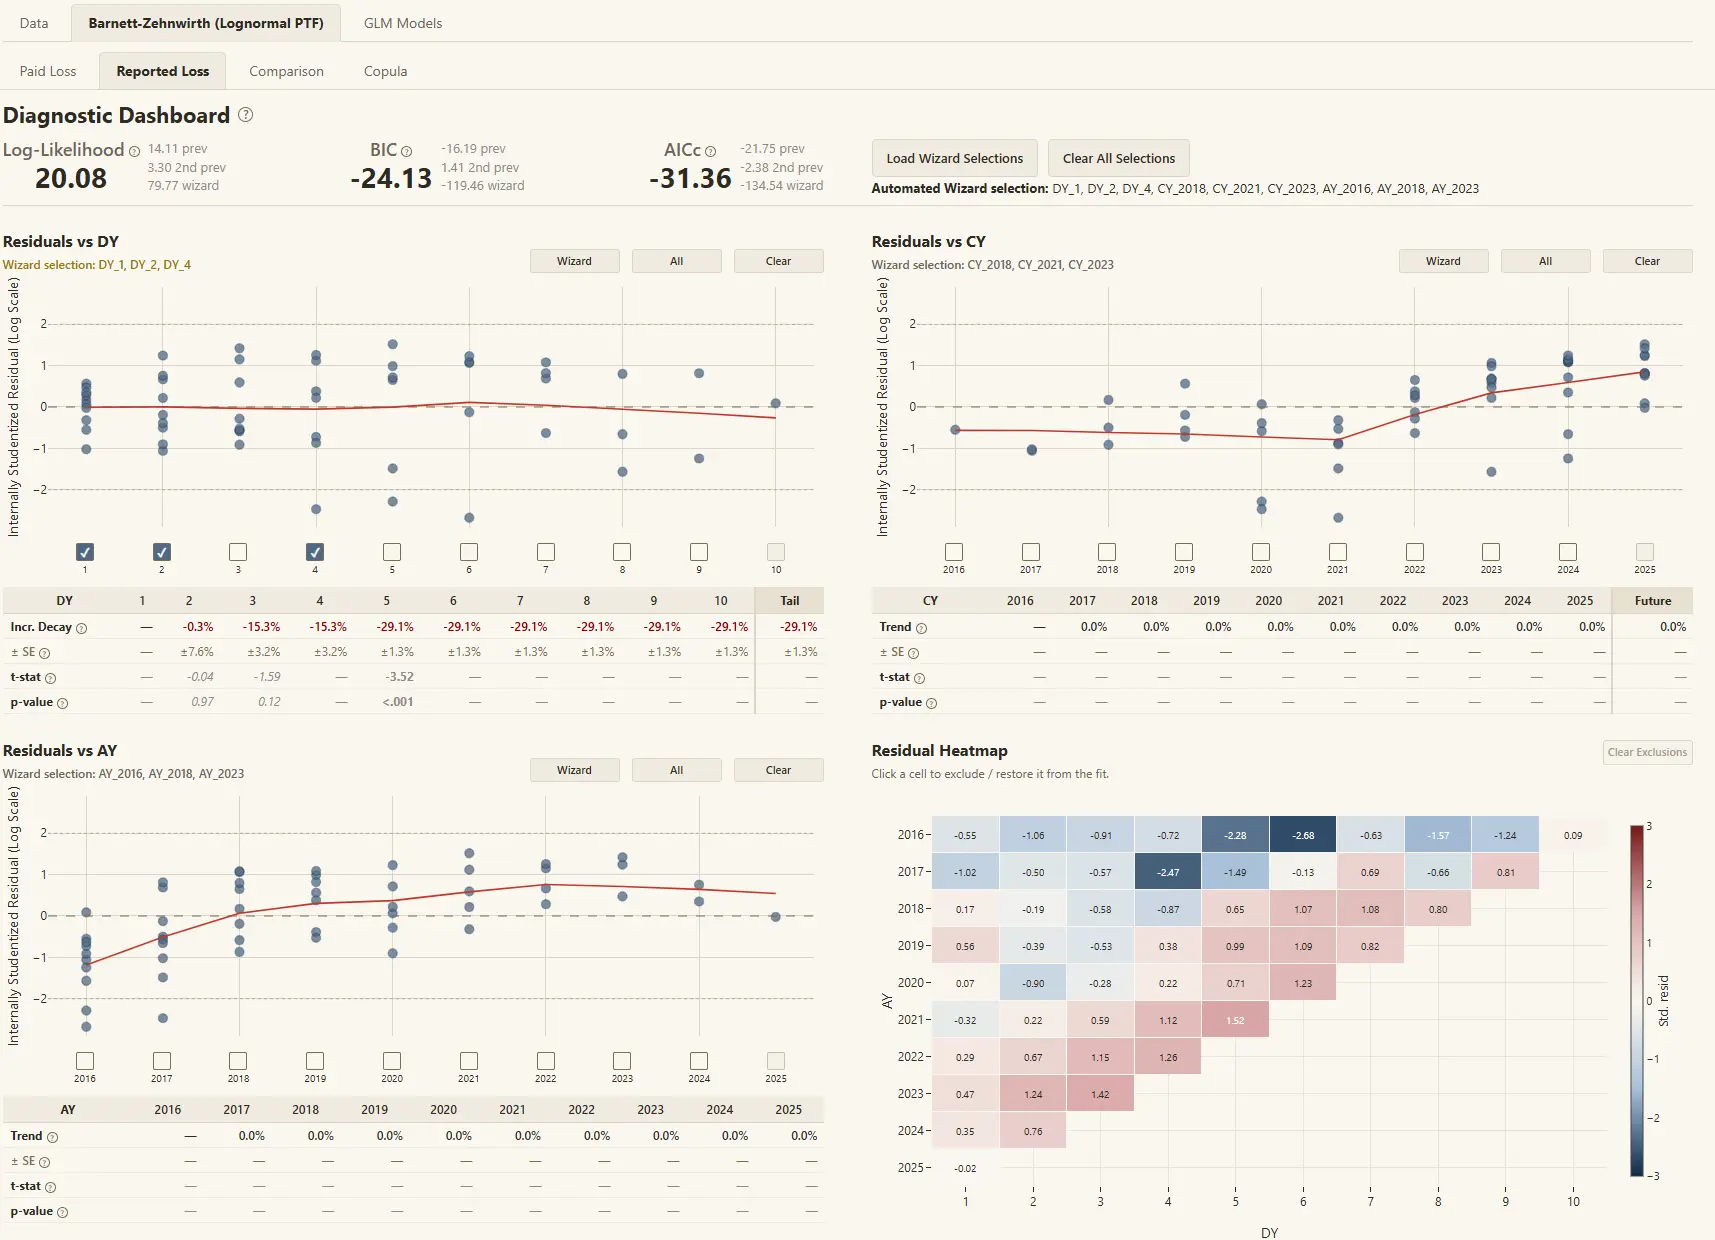
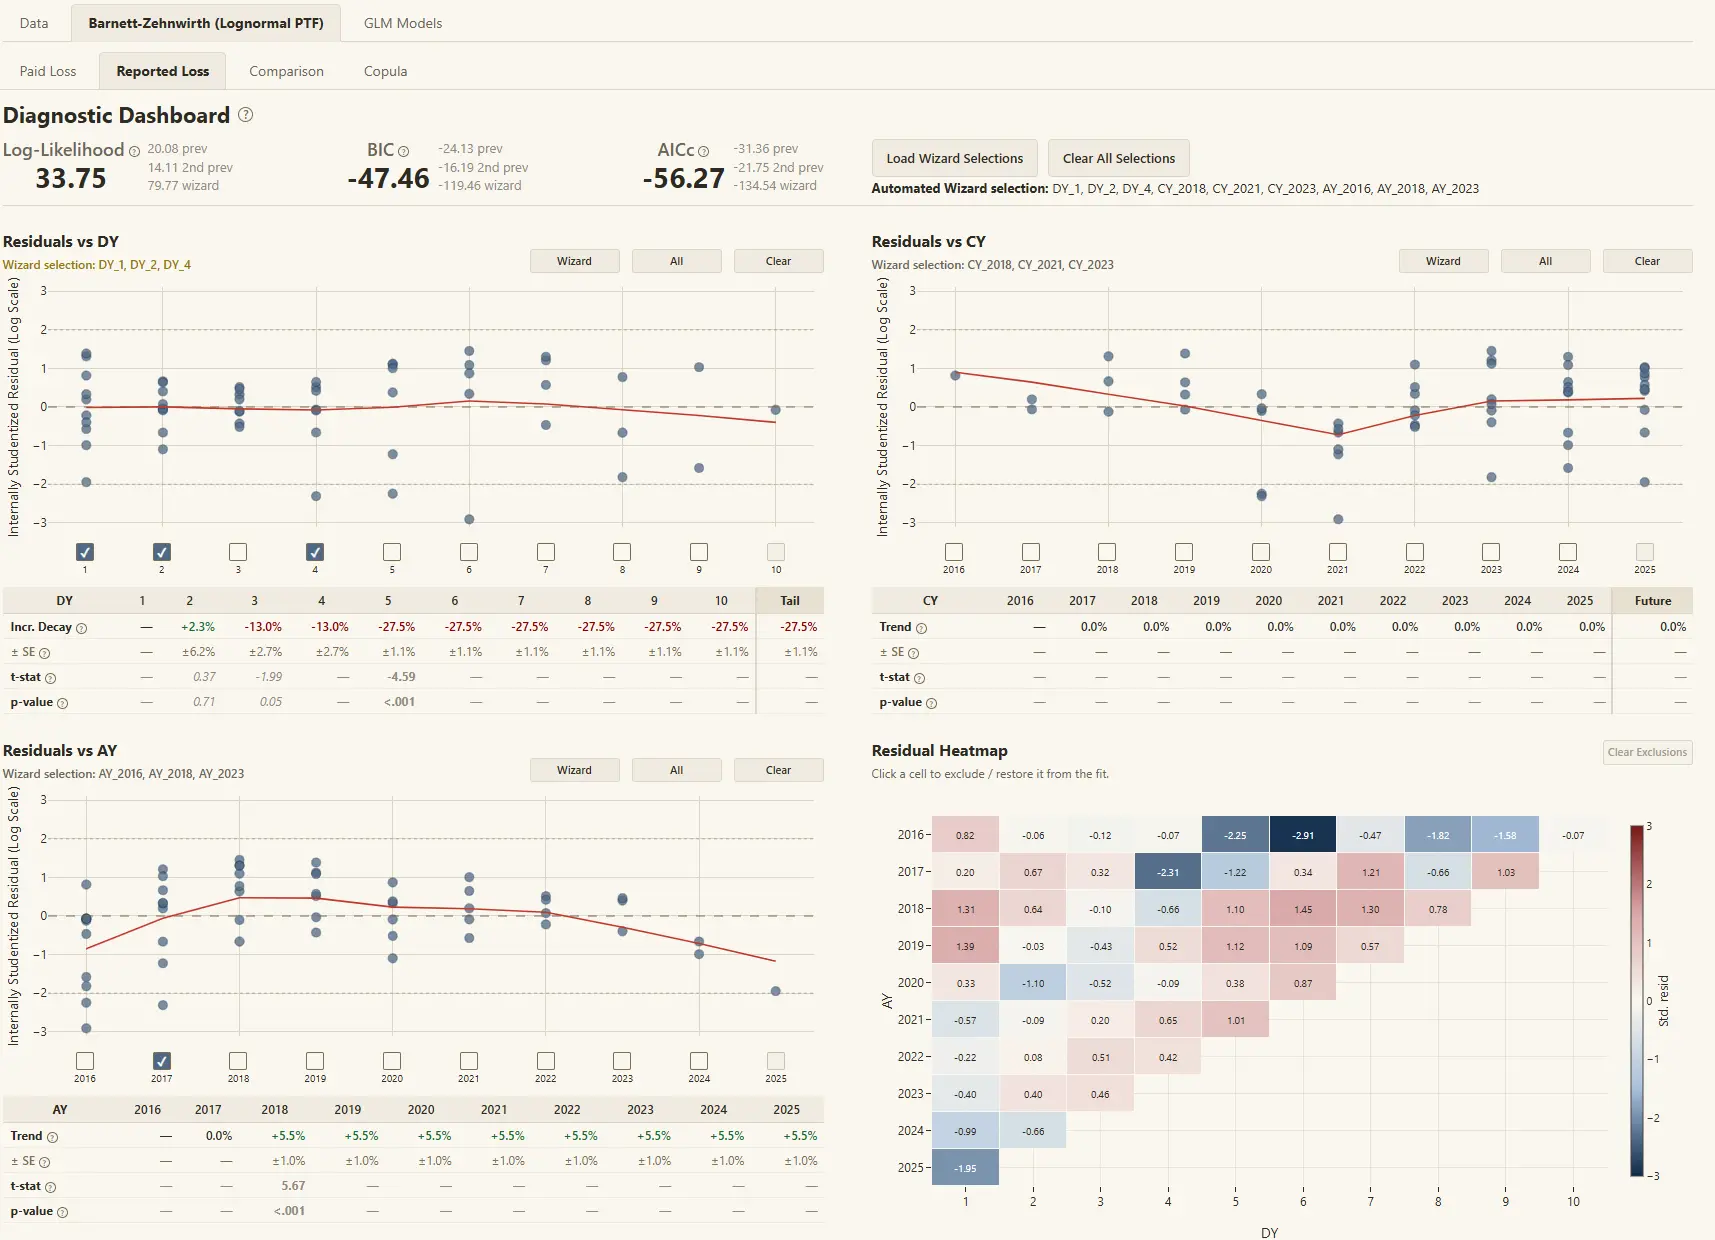
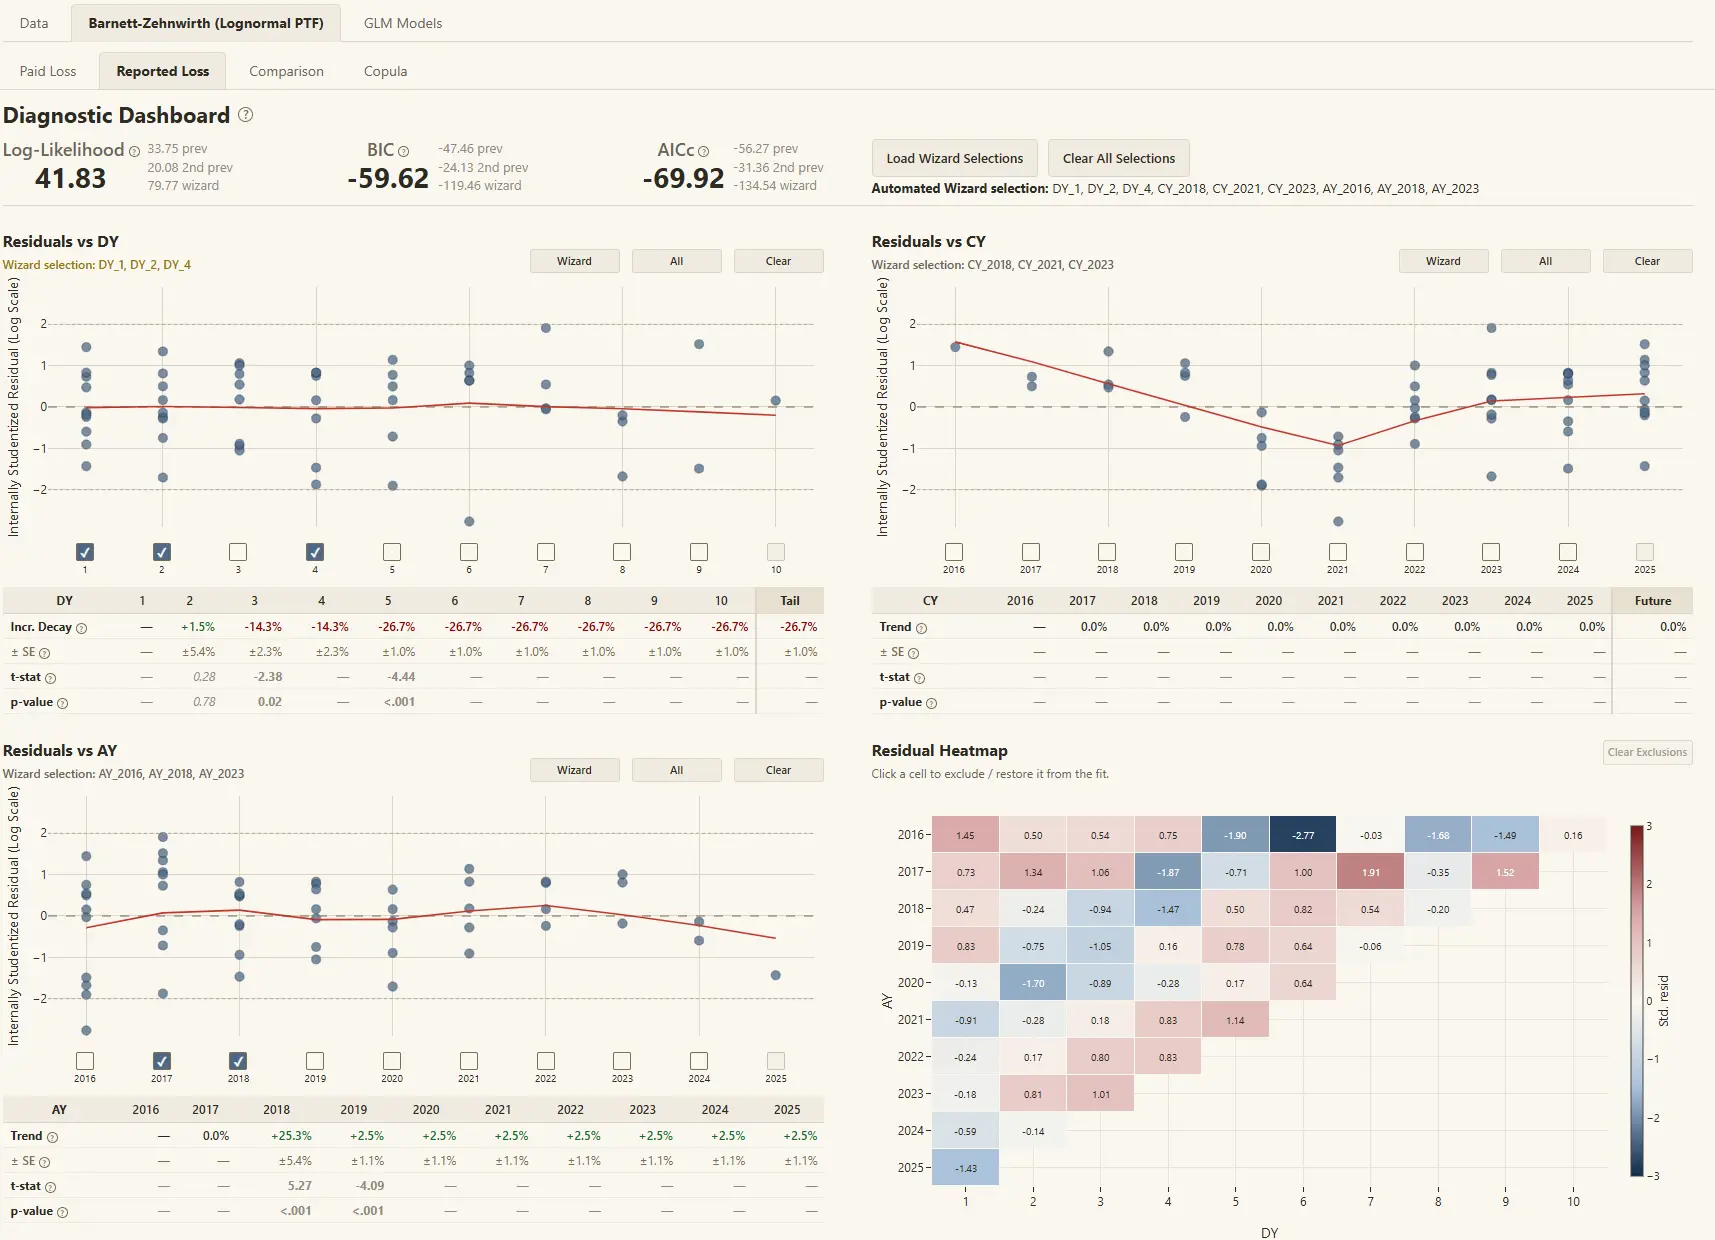
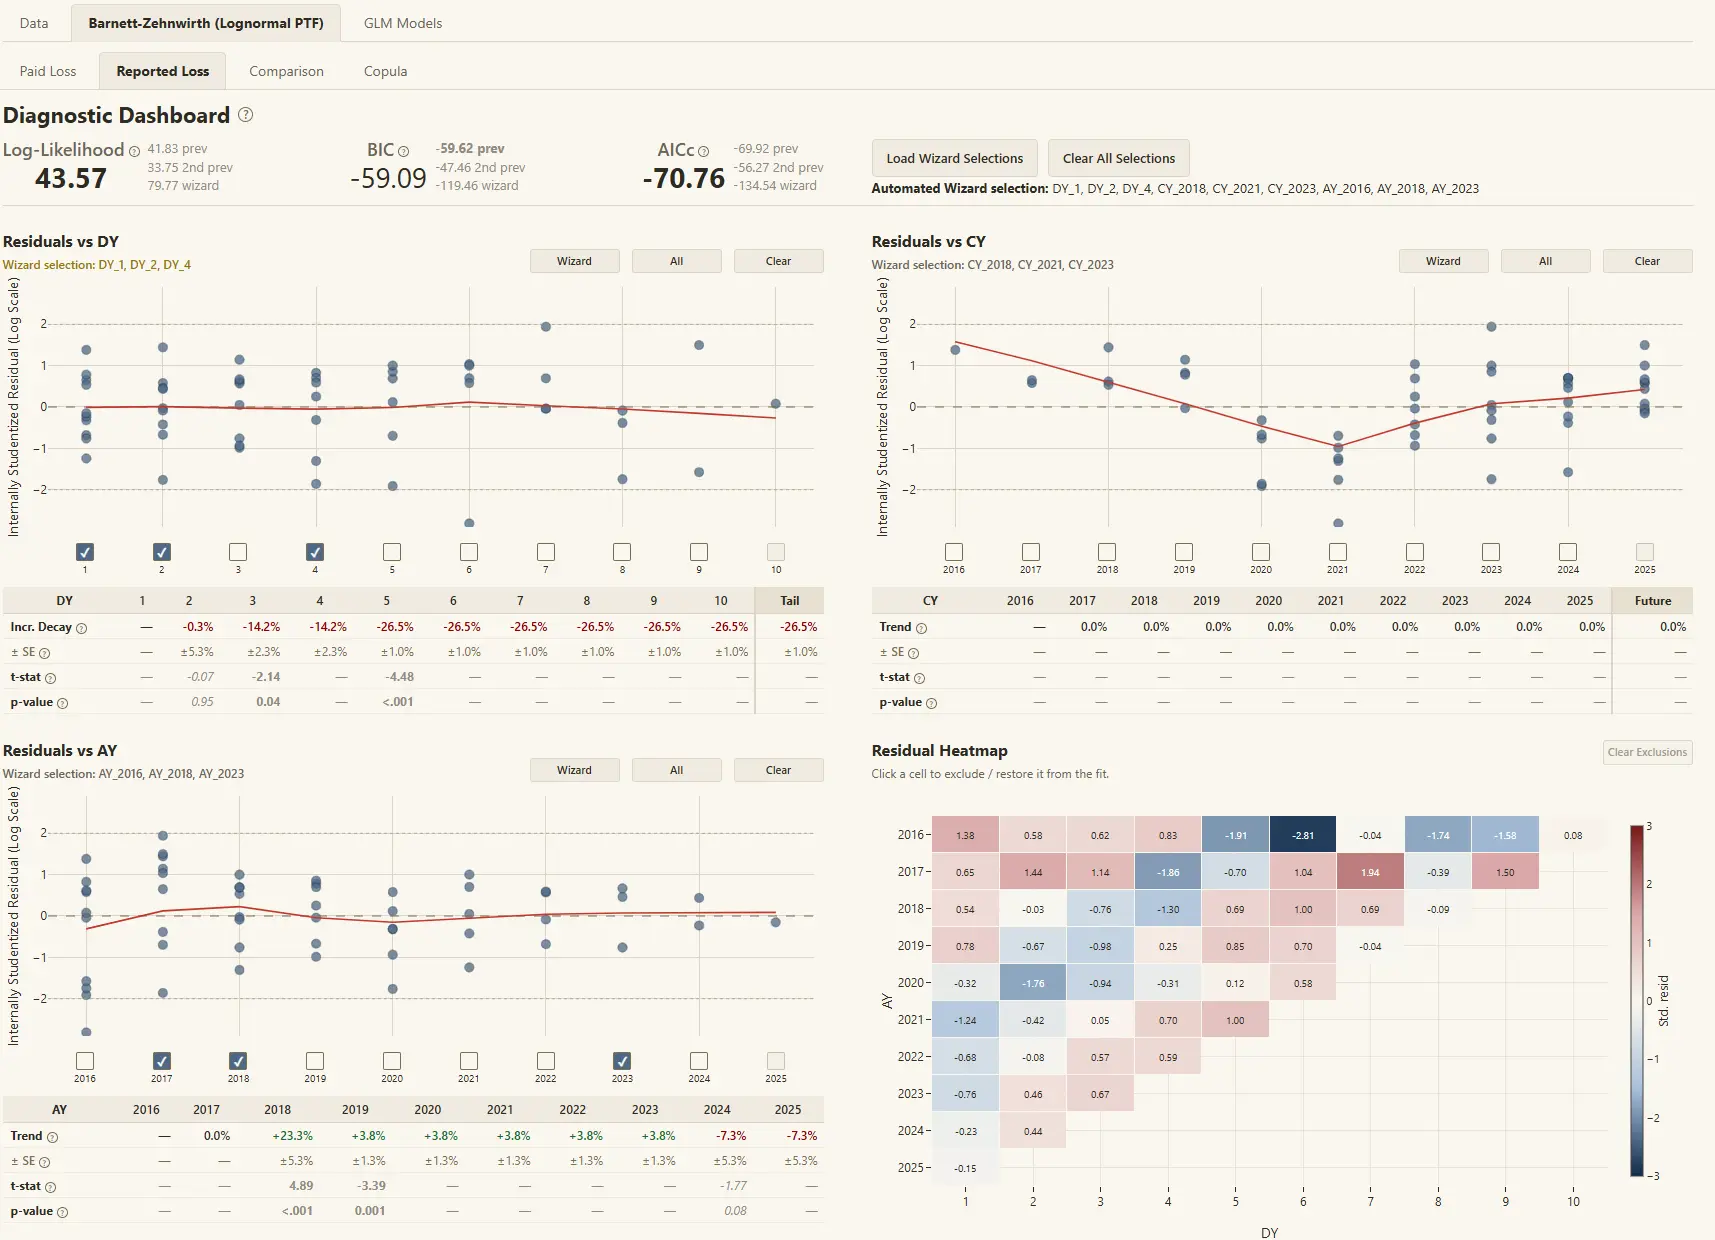
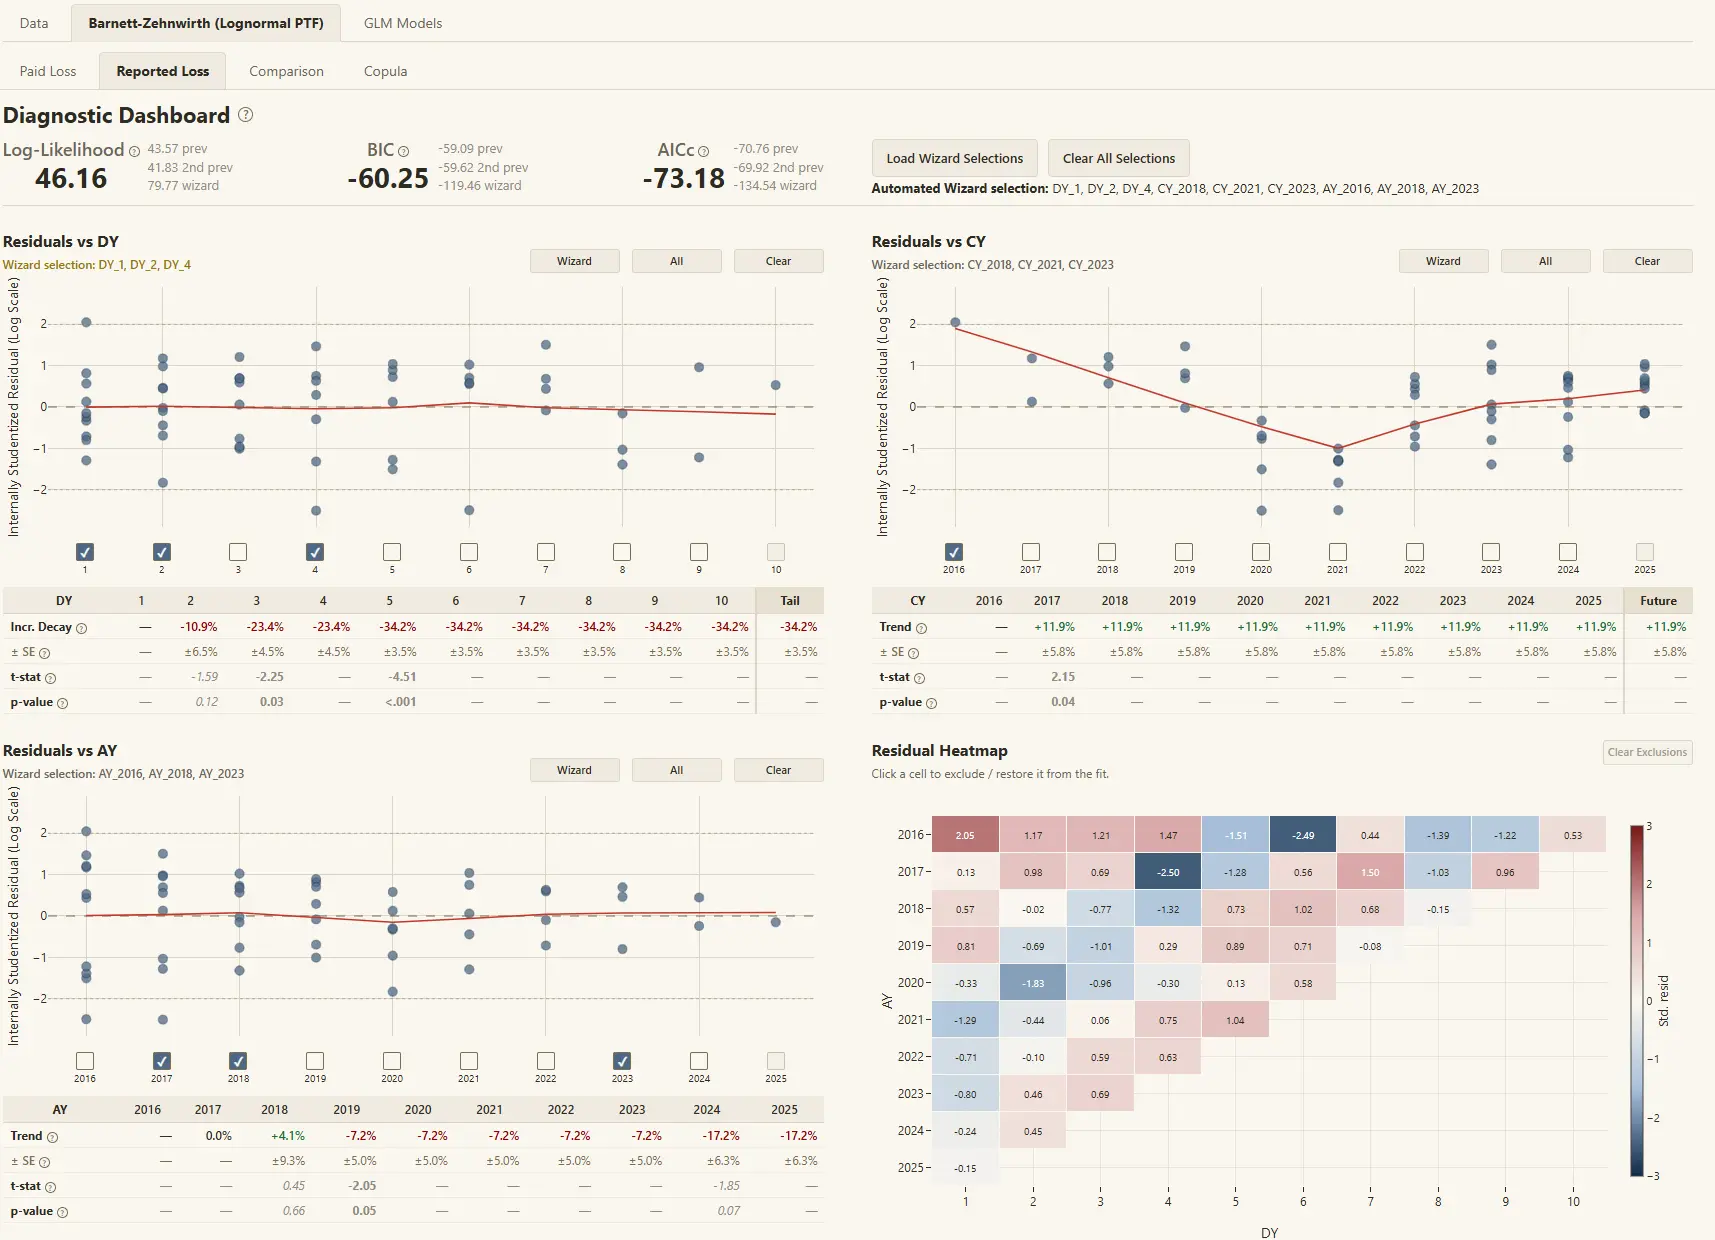
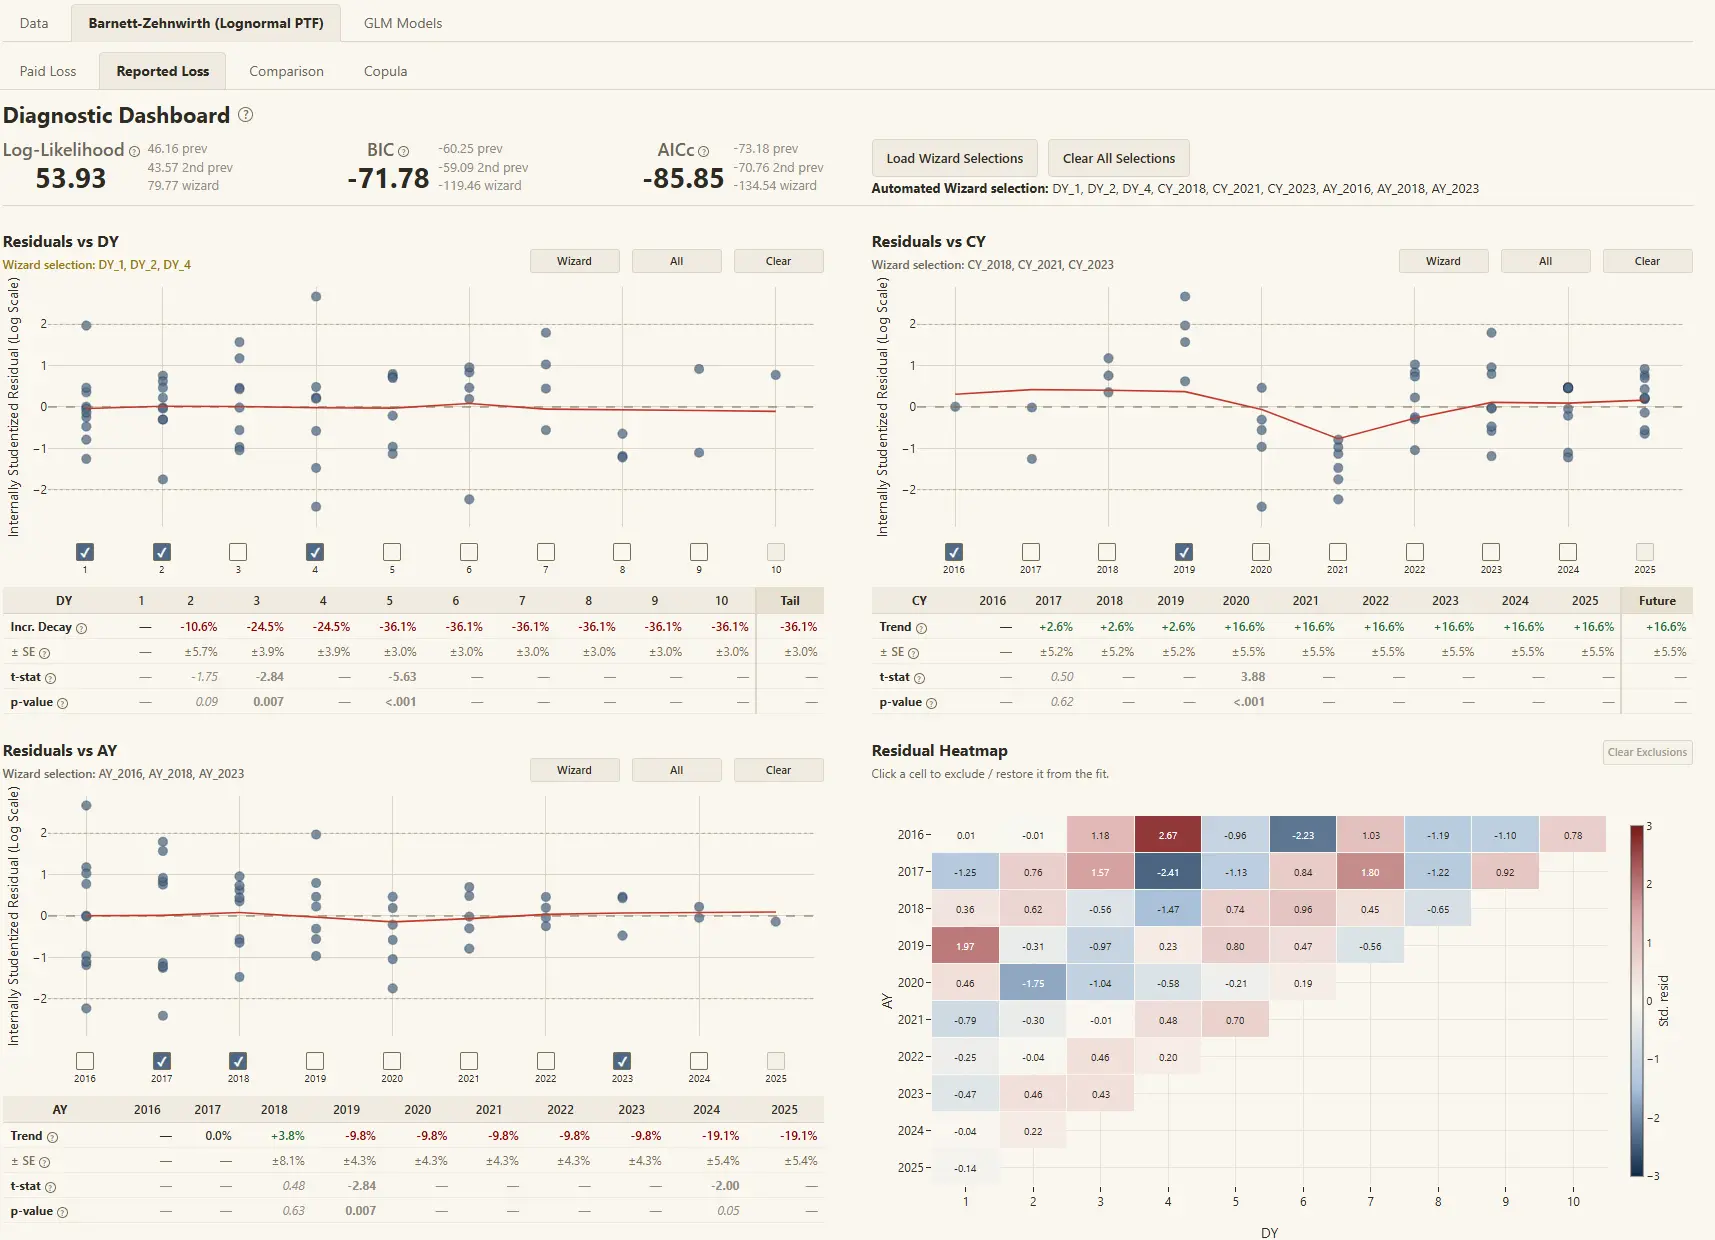
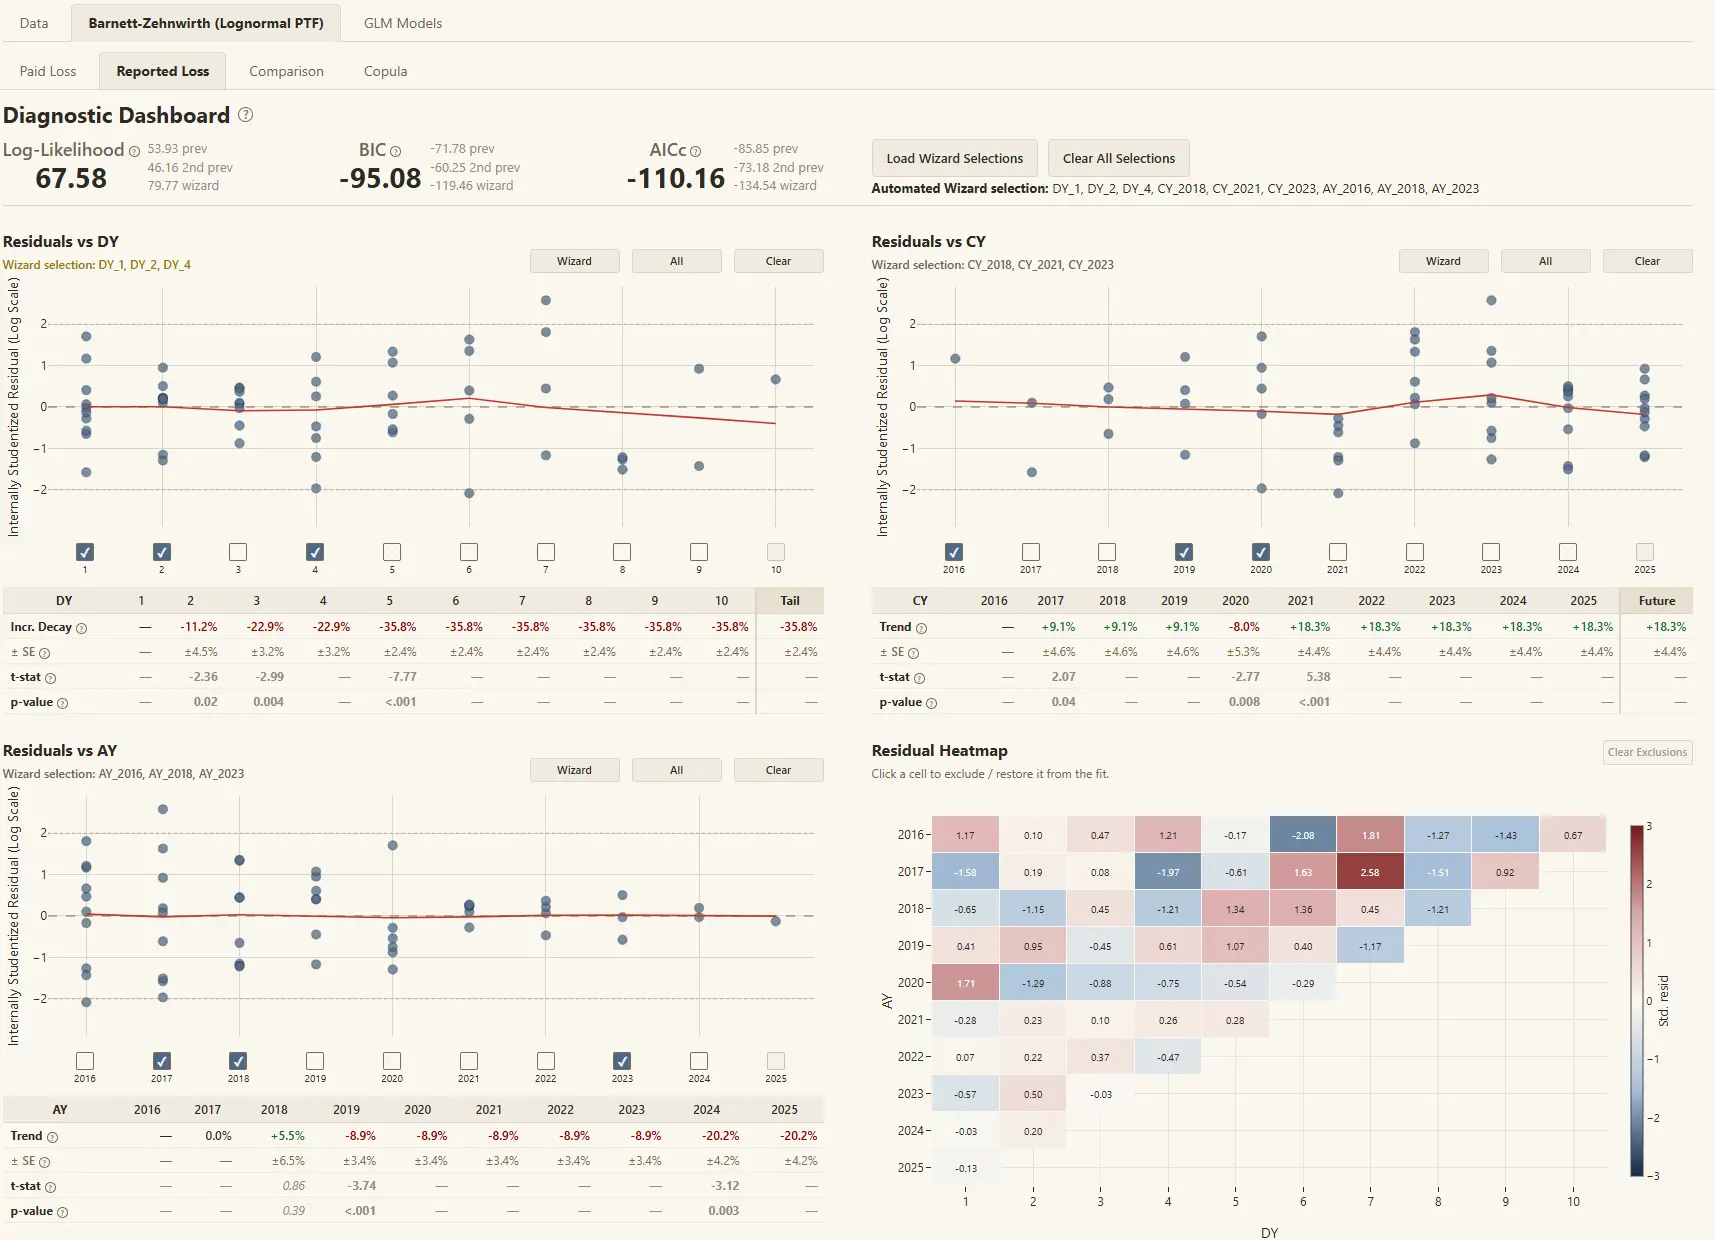
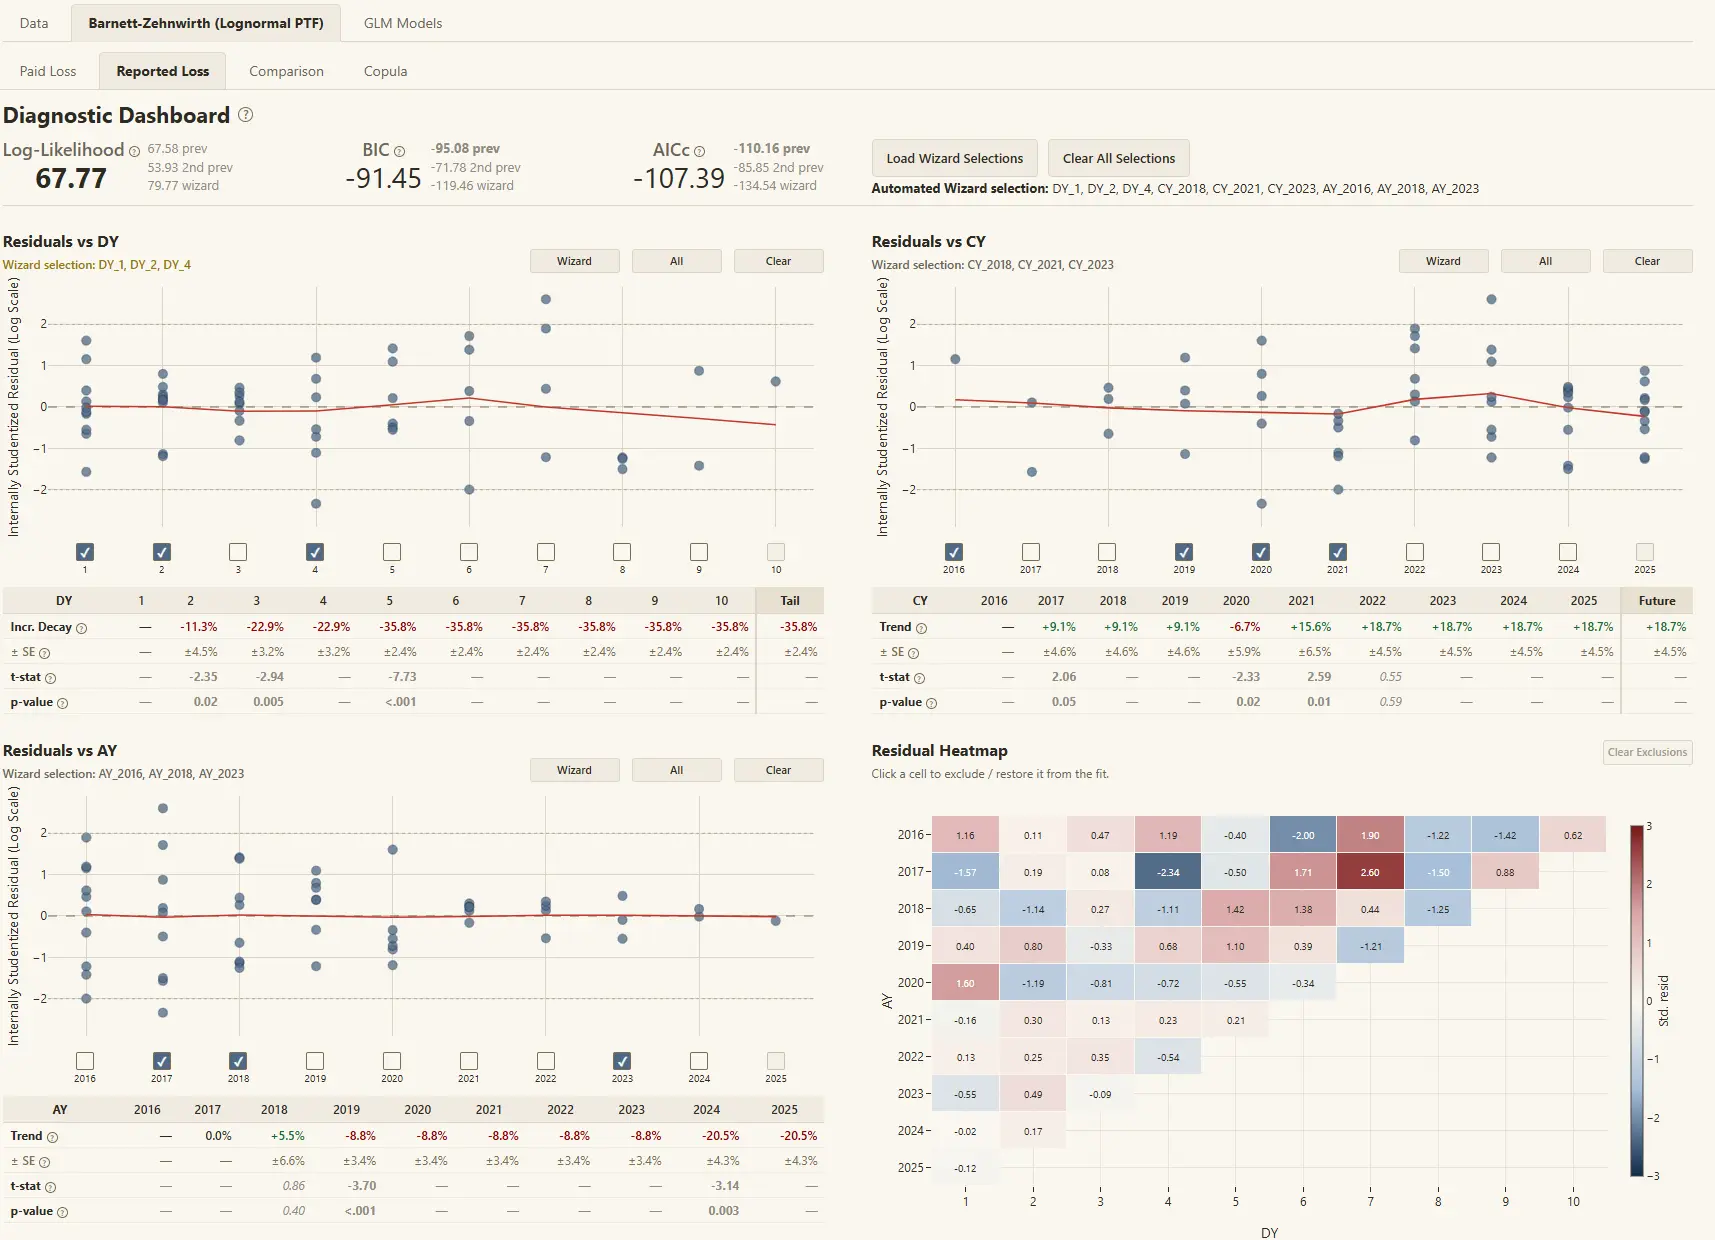
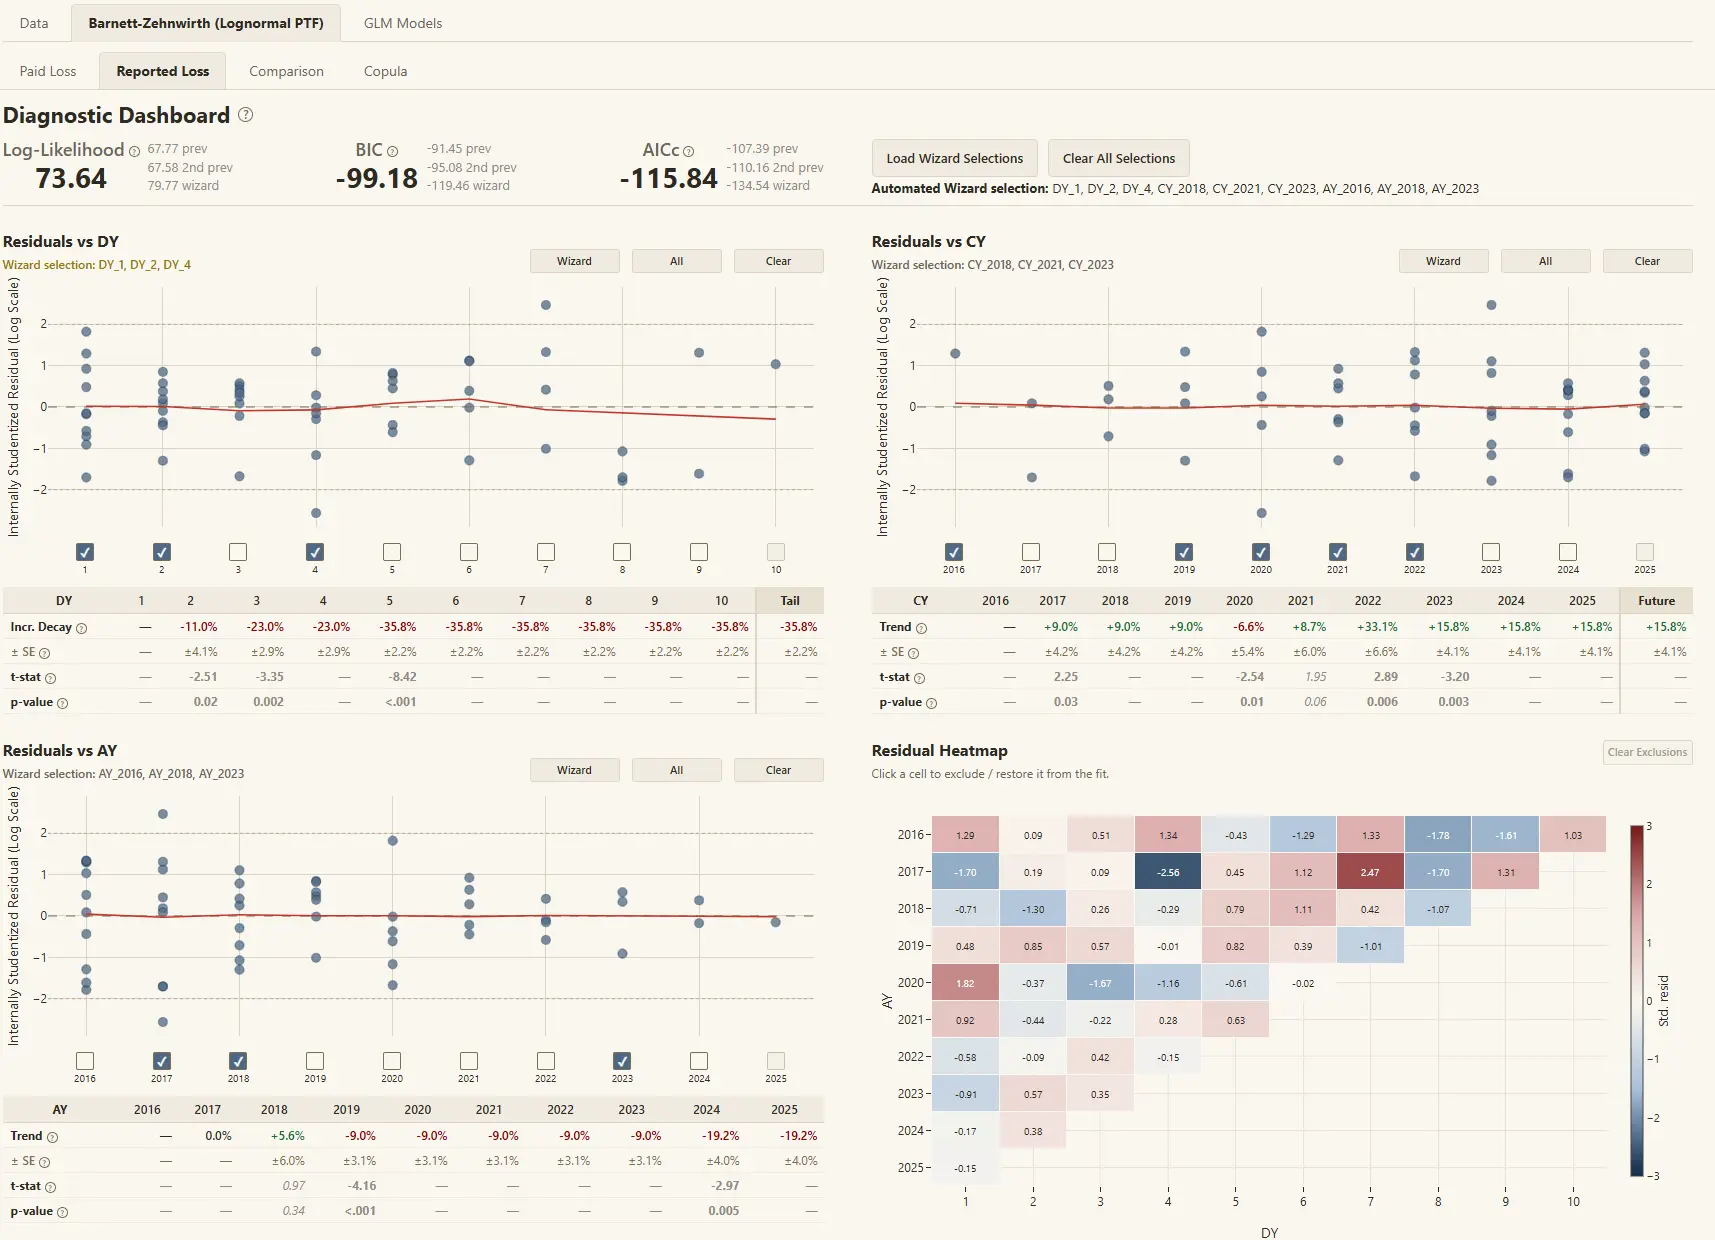
The customizable model structure allows the user to select from various model forms, including the Barnett-Zehnwirth Probabilistic Trend Family (PTF) modeling framework, widely considered the gold standard of stochastic reserving methods and described in their paper “Best Estimates for Reserves” (published in the Proceedings of the CAS, Volume LXXXVII, 2000), and the GLM family distributions: ODP, Gamma, Inverse Gaussian, and Tweedie.
Each model links the variance to the mean, but the GLM families fix that relationship across the entire triangle, while the PTF framework allows it to change across development periods (e.g., higher percentage variability is often appropriate for later development periods, which remain noisy even as the incremental mean becomes small), which is often a material enhancement. All of these structures provide clear advantages over the traditional two-dimensional ODP Bootstrap (simplified GLM) stochastic model, in both insight and control.
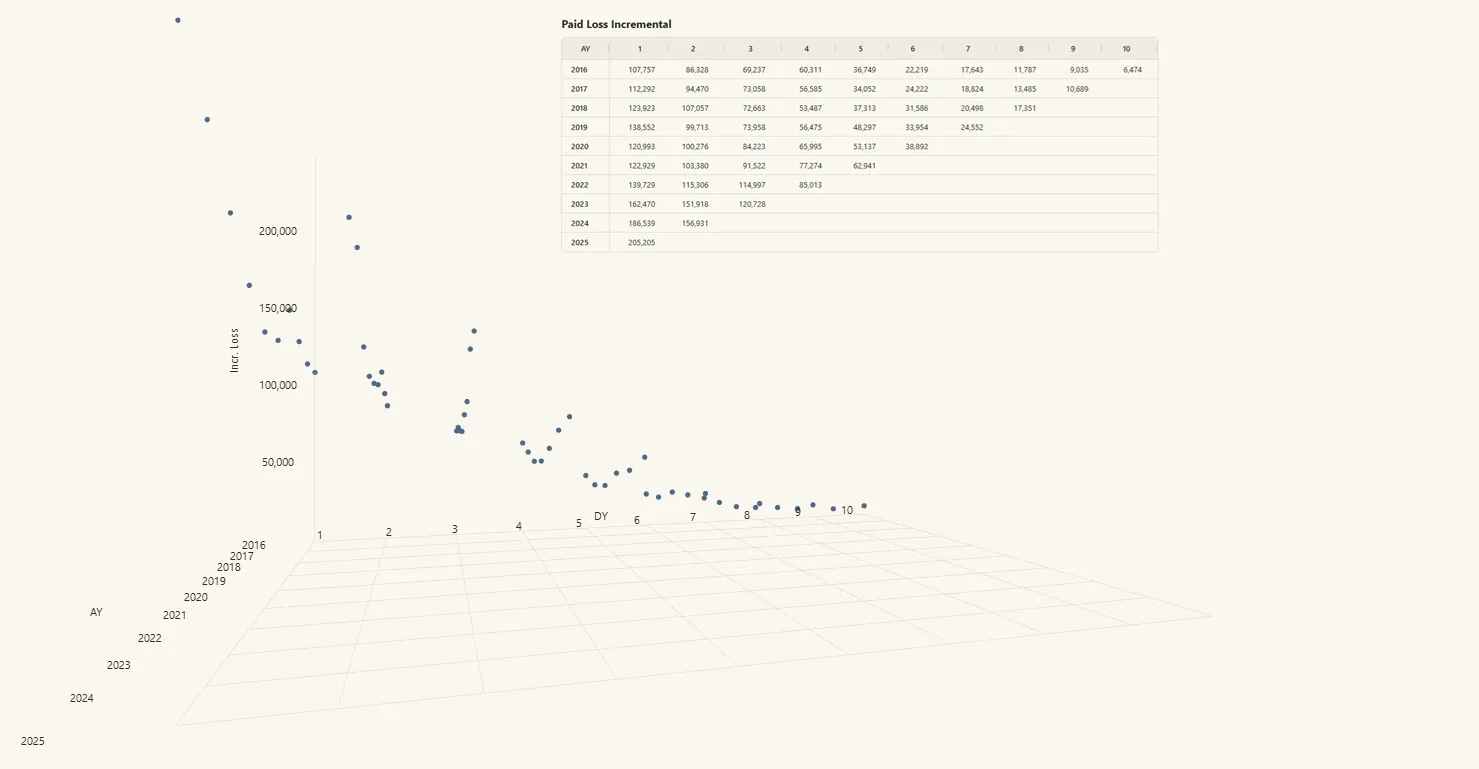
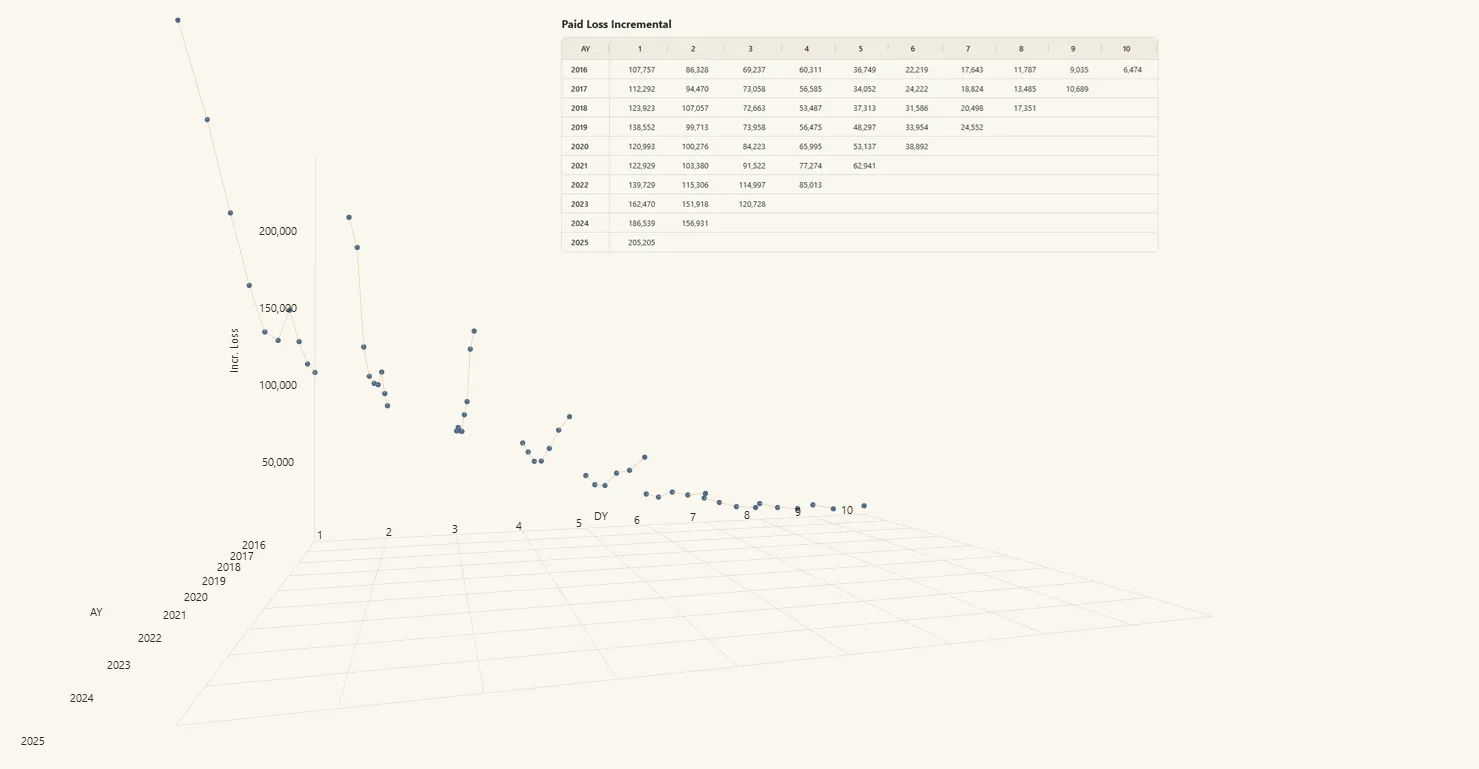
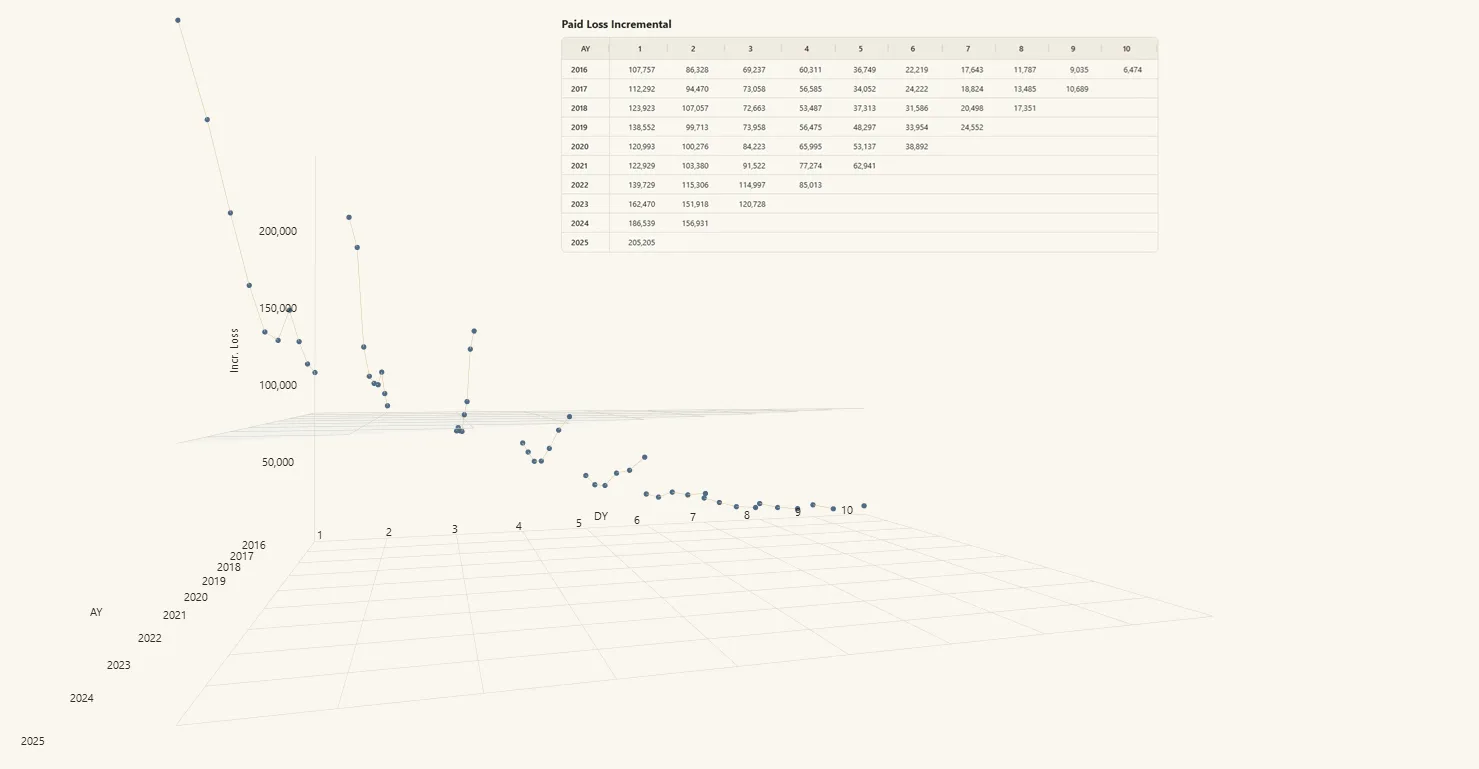
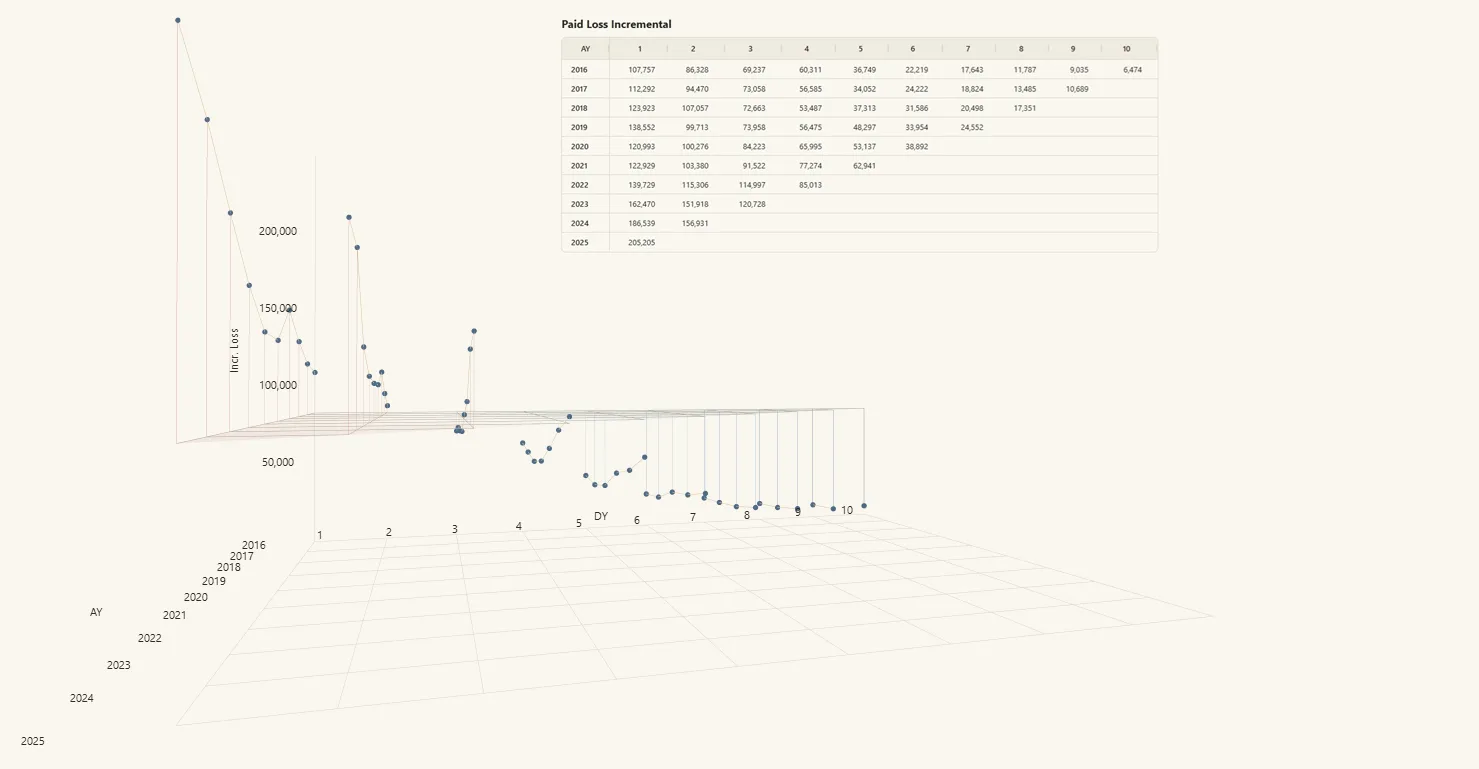
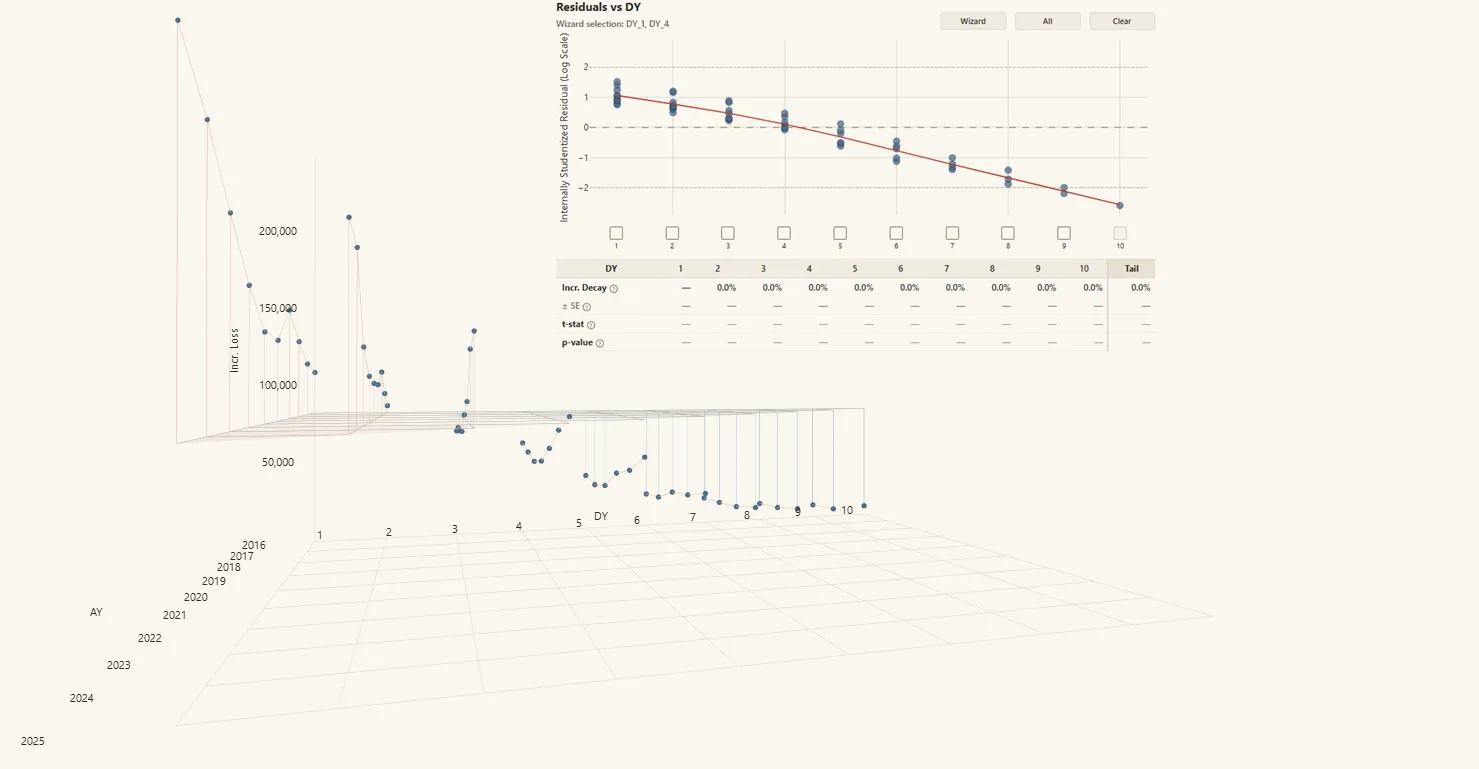
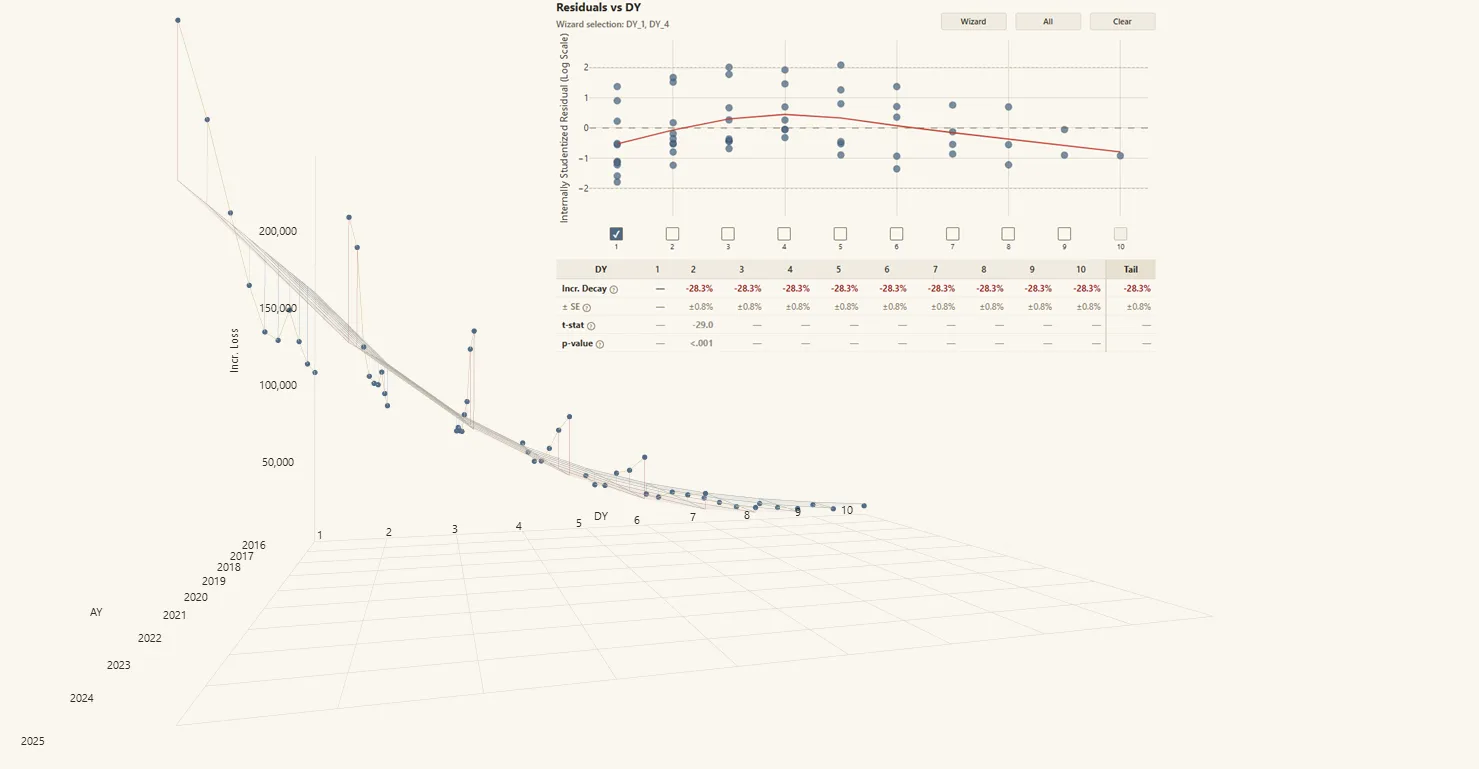
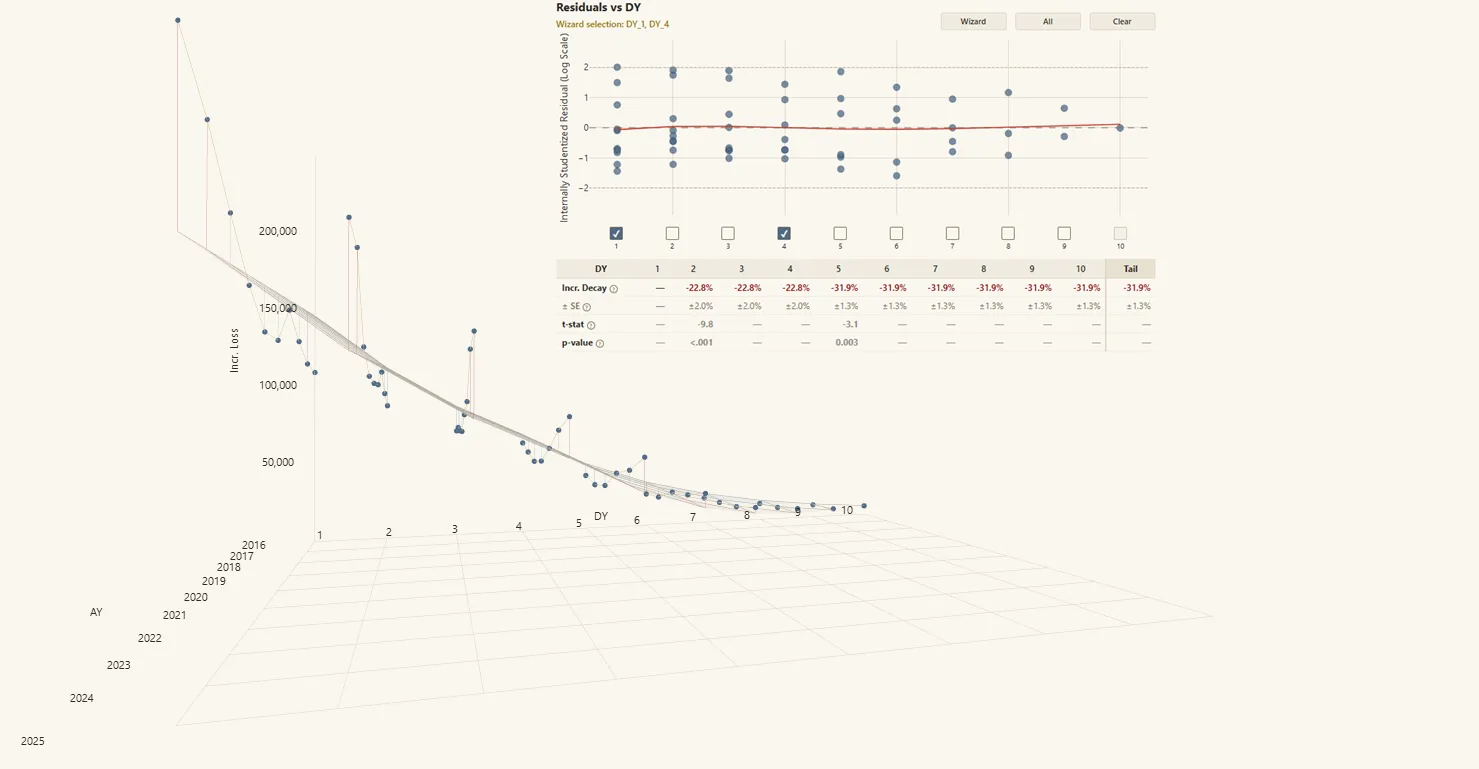
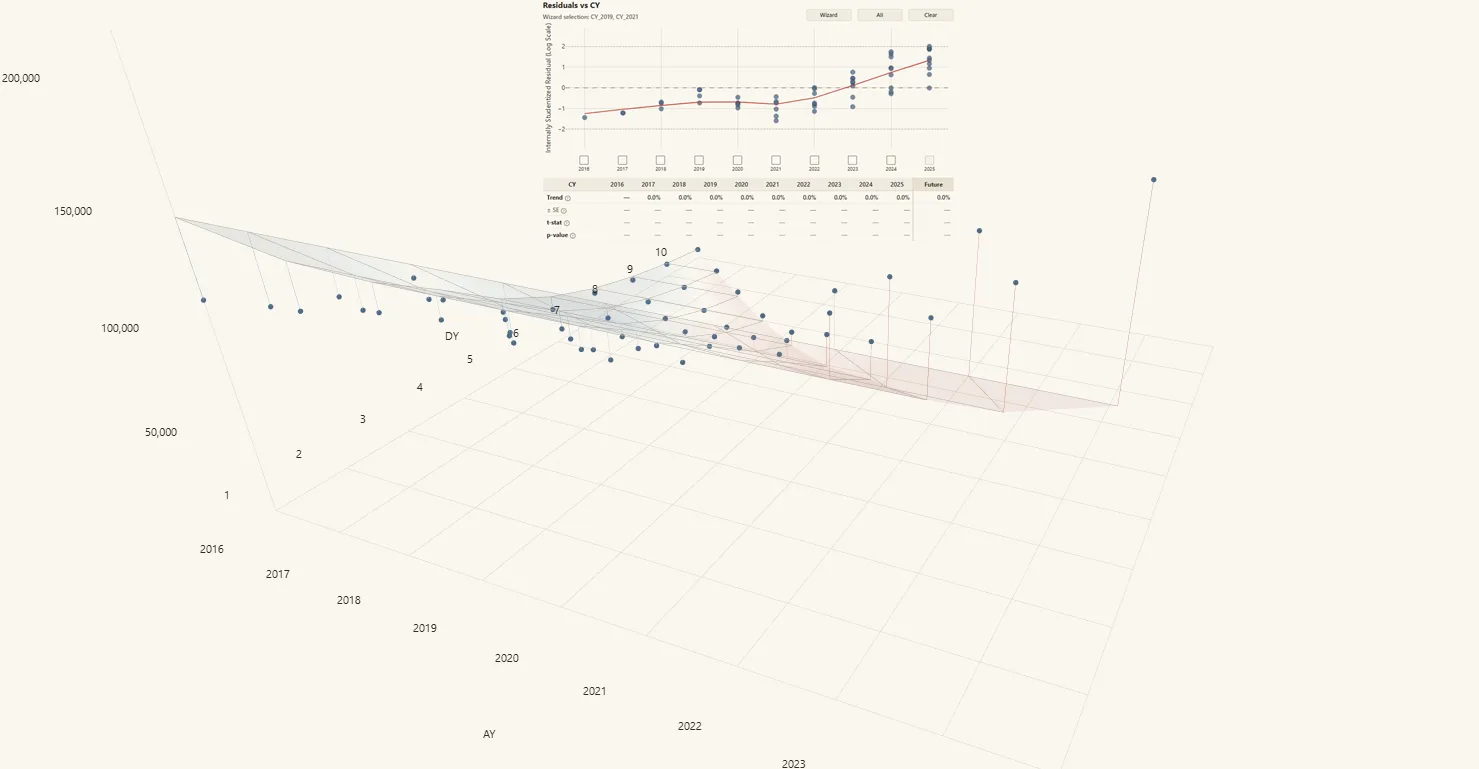
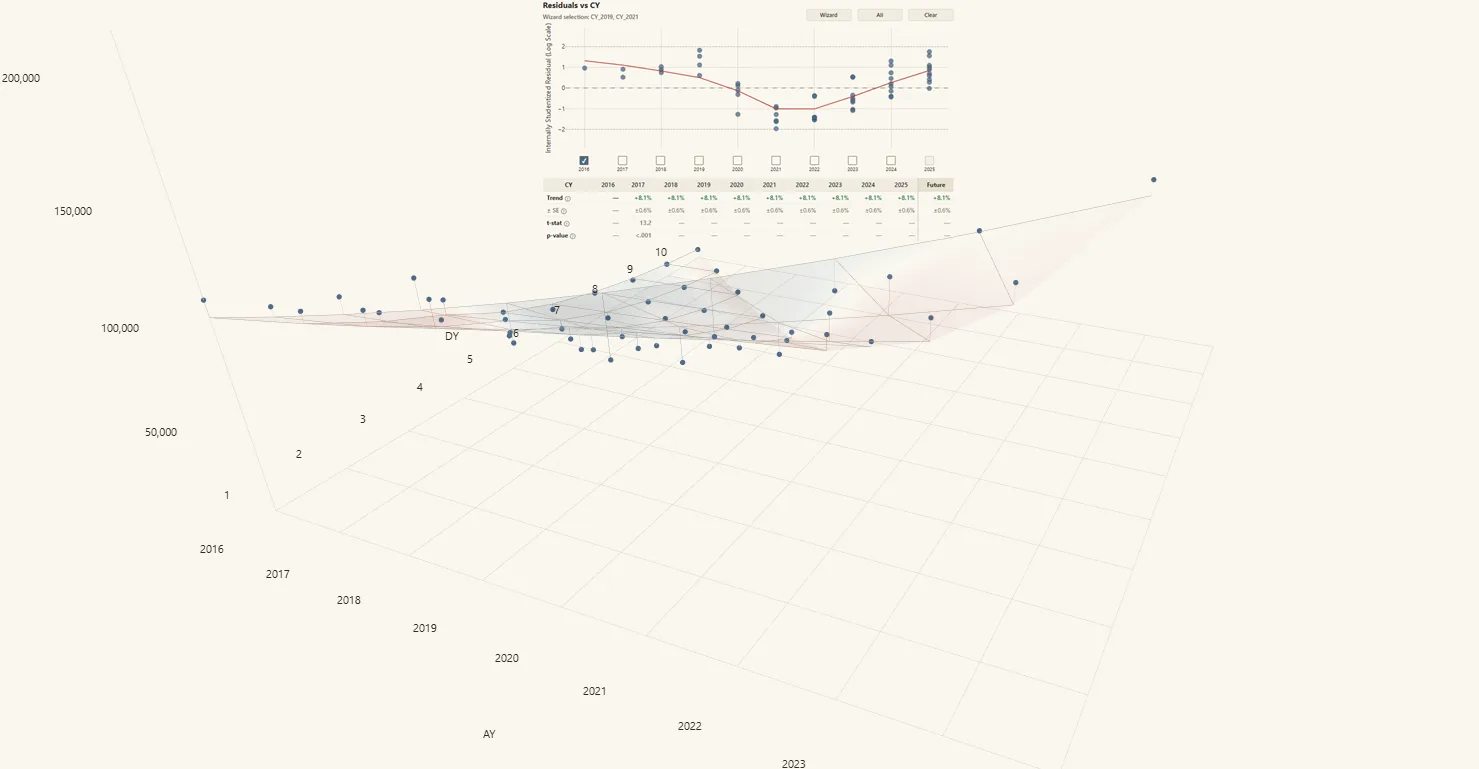
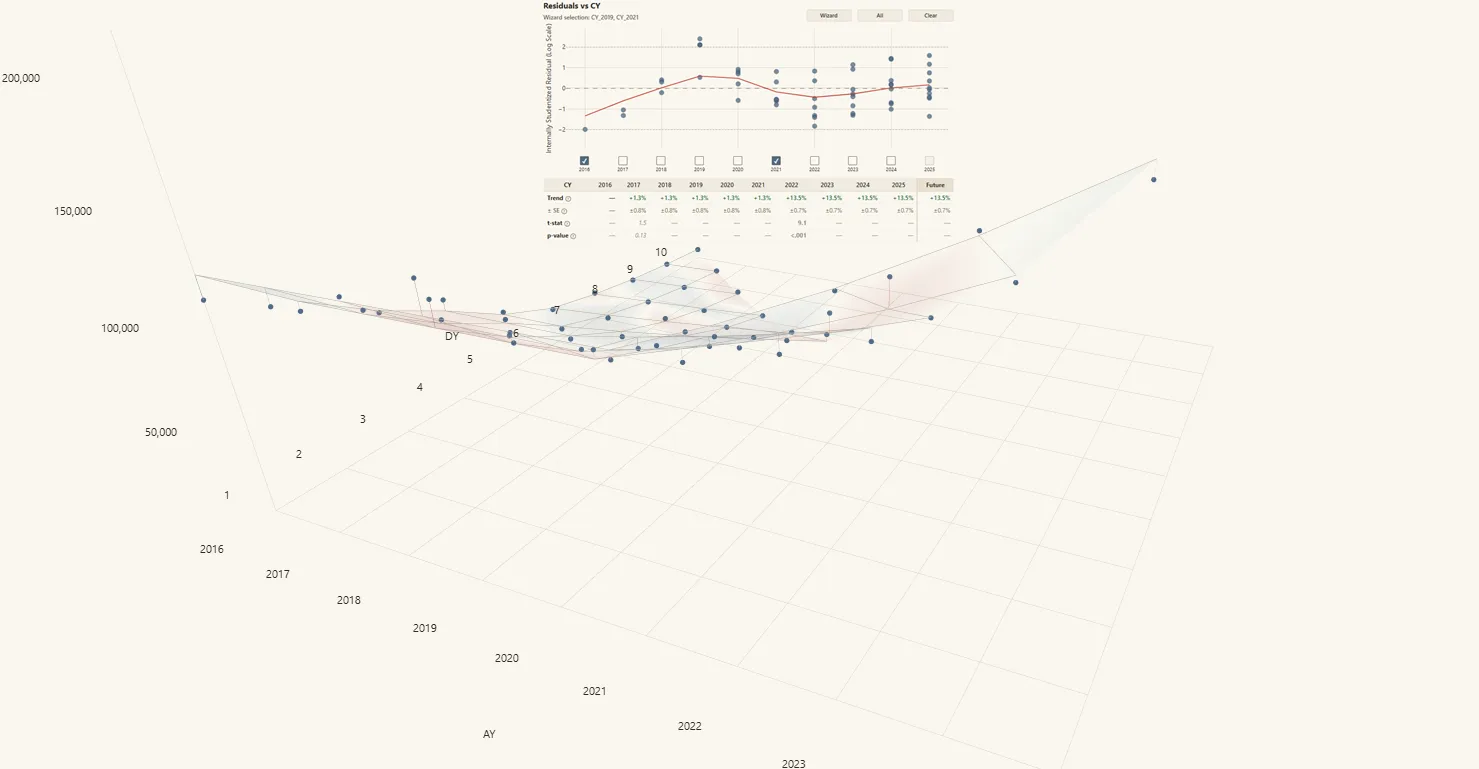
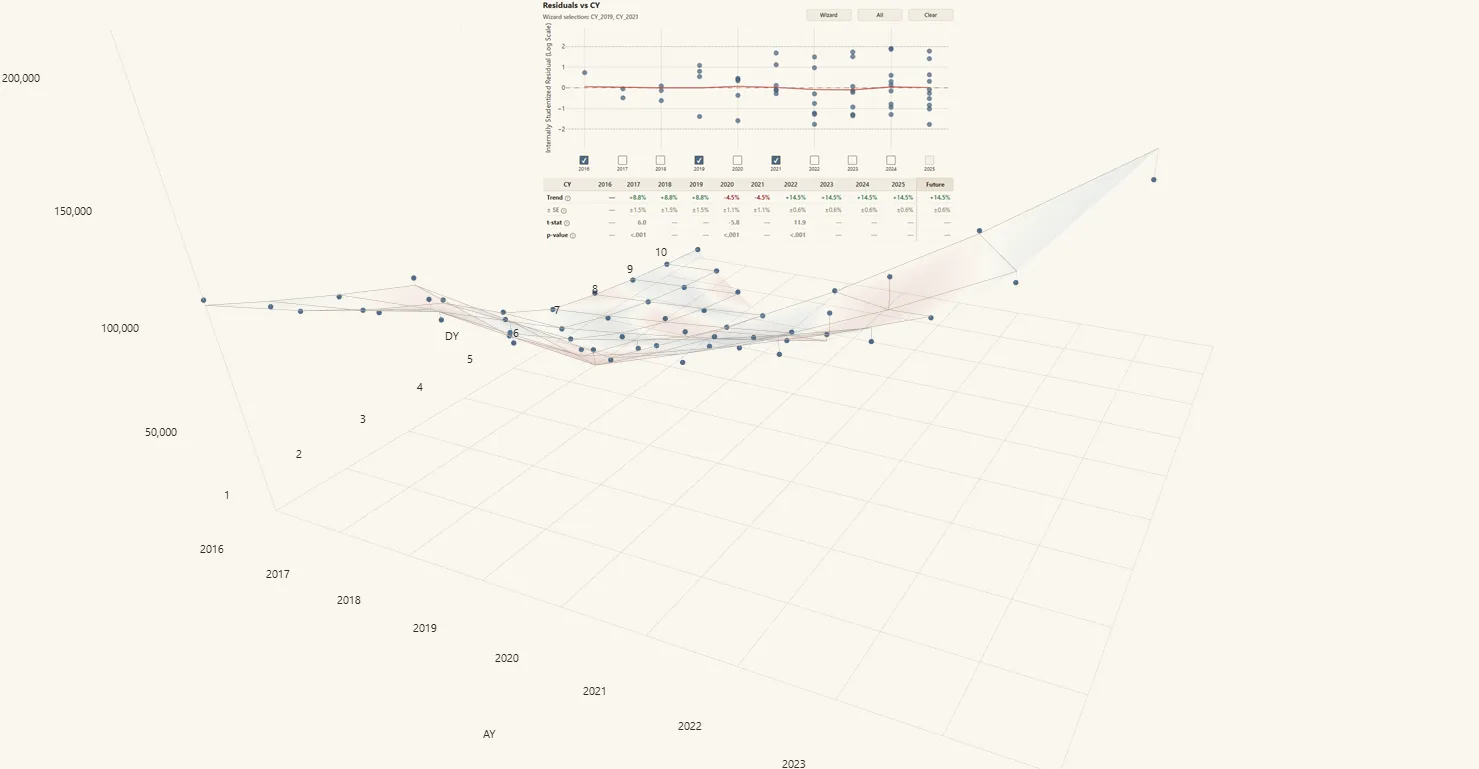
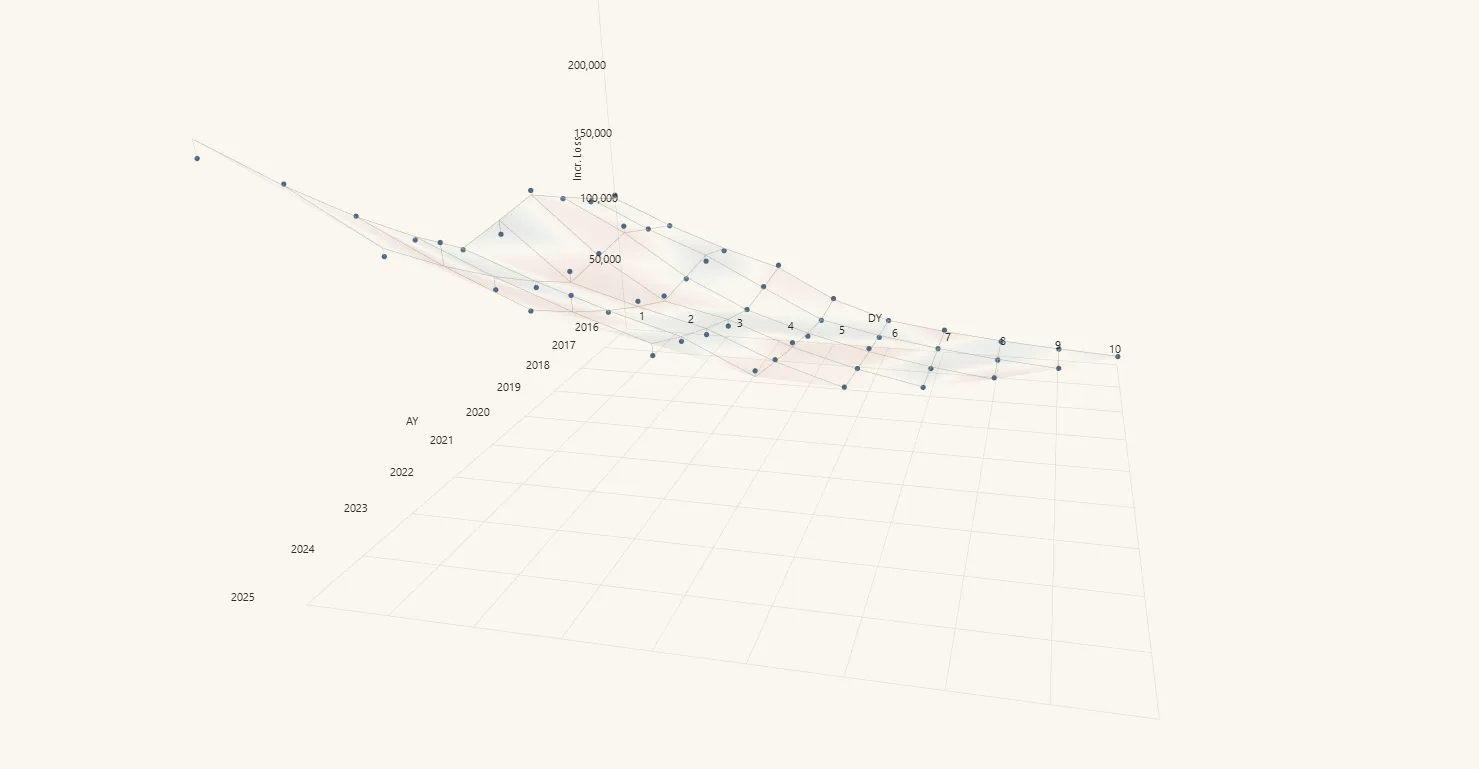
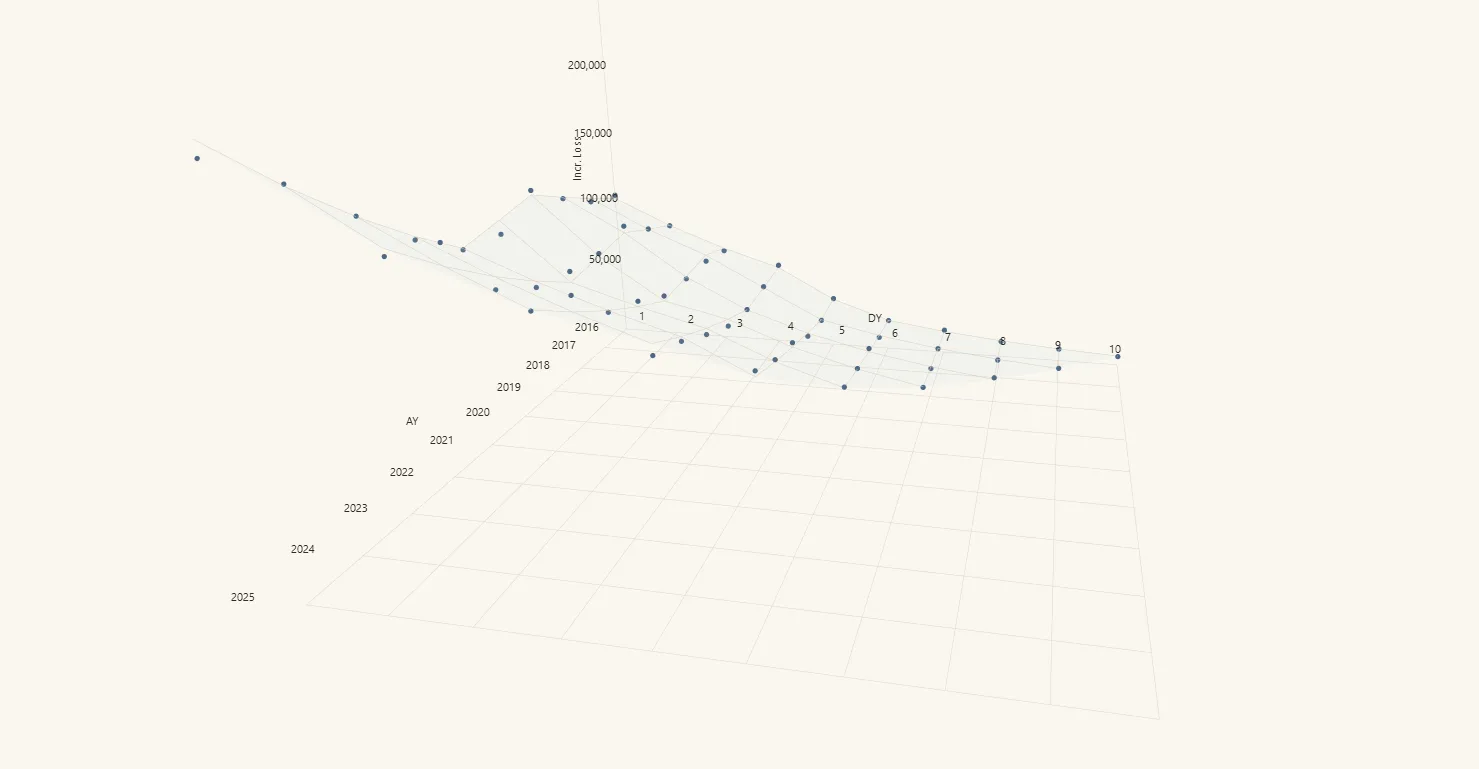
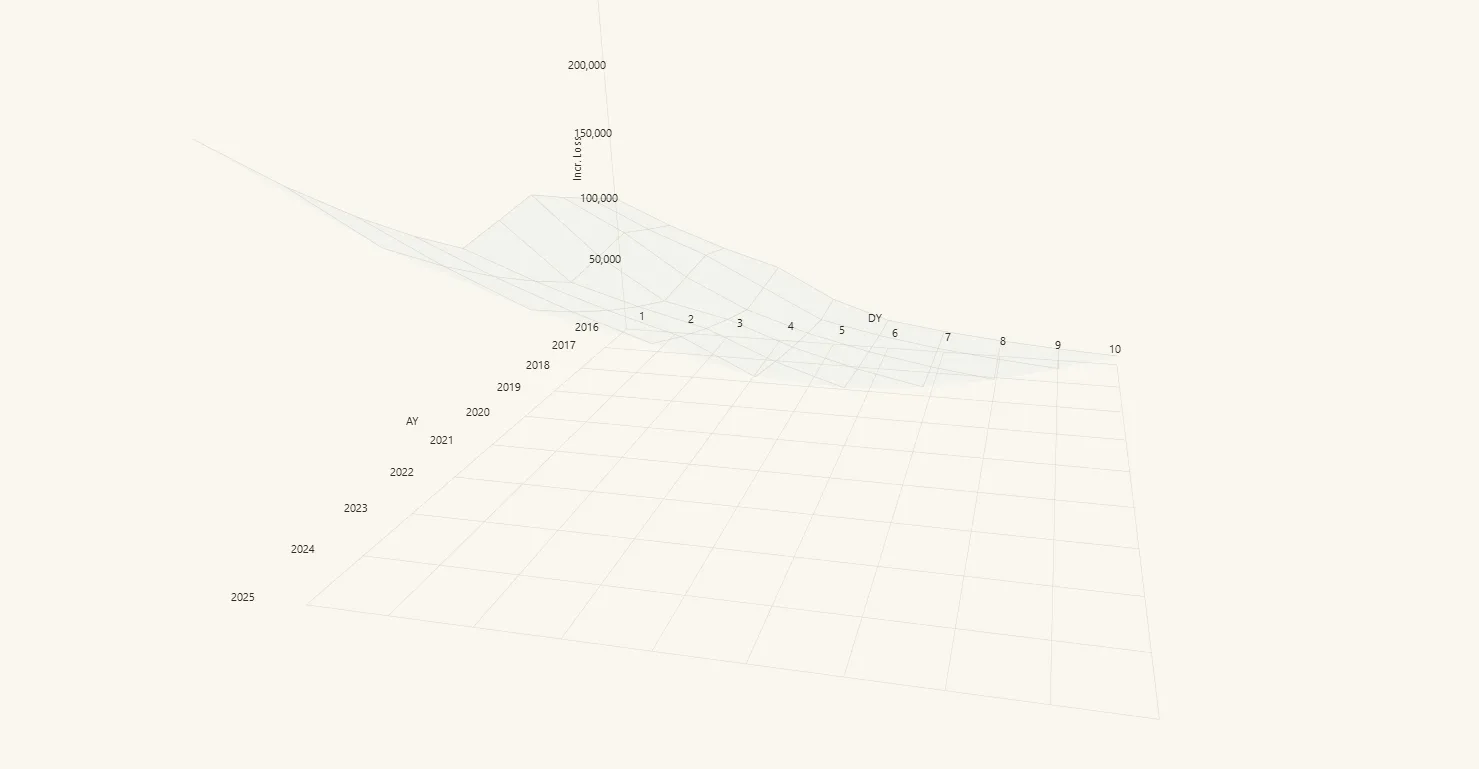
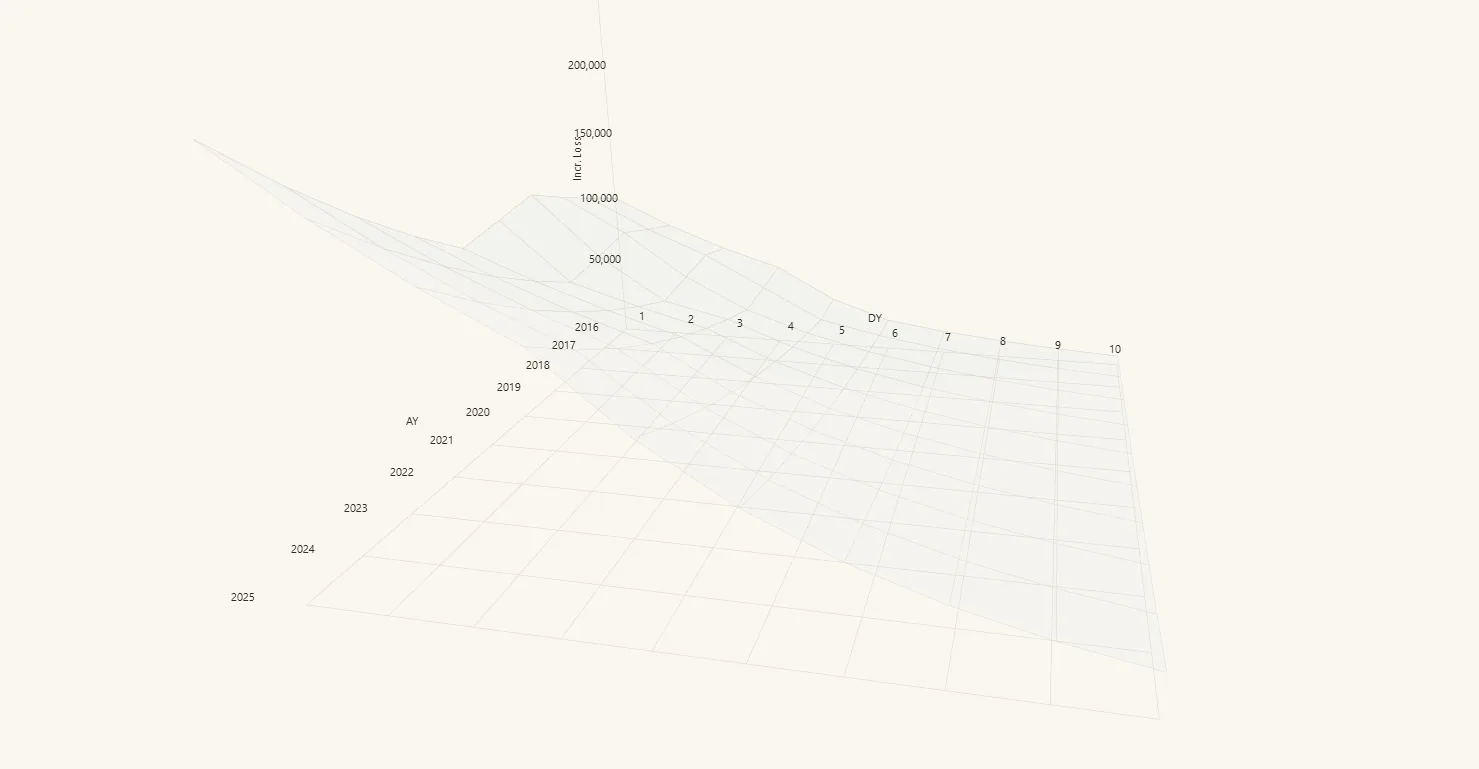
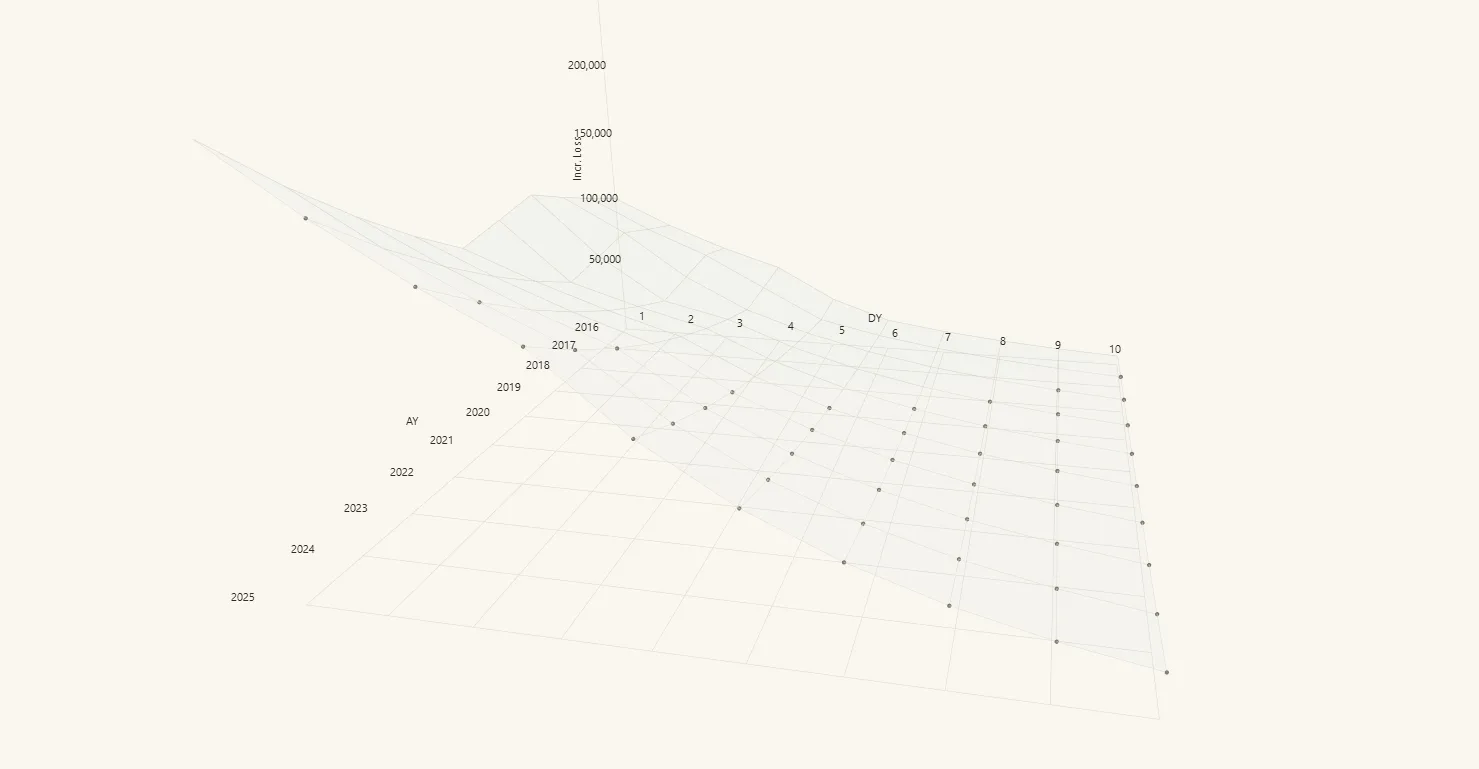
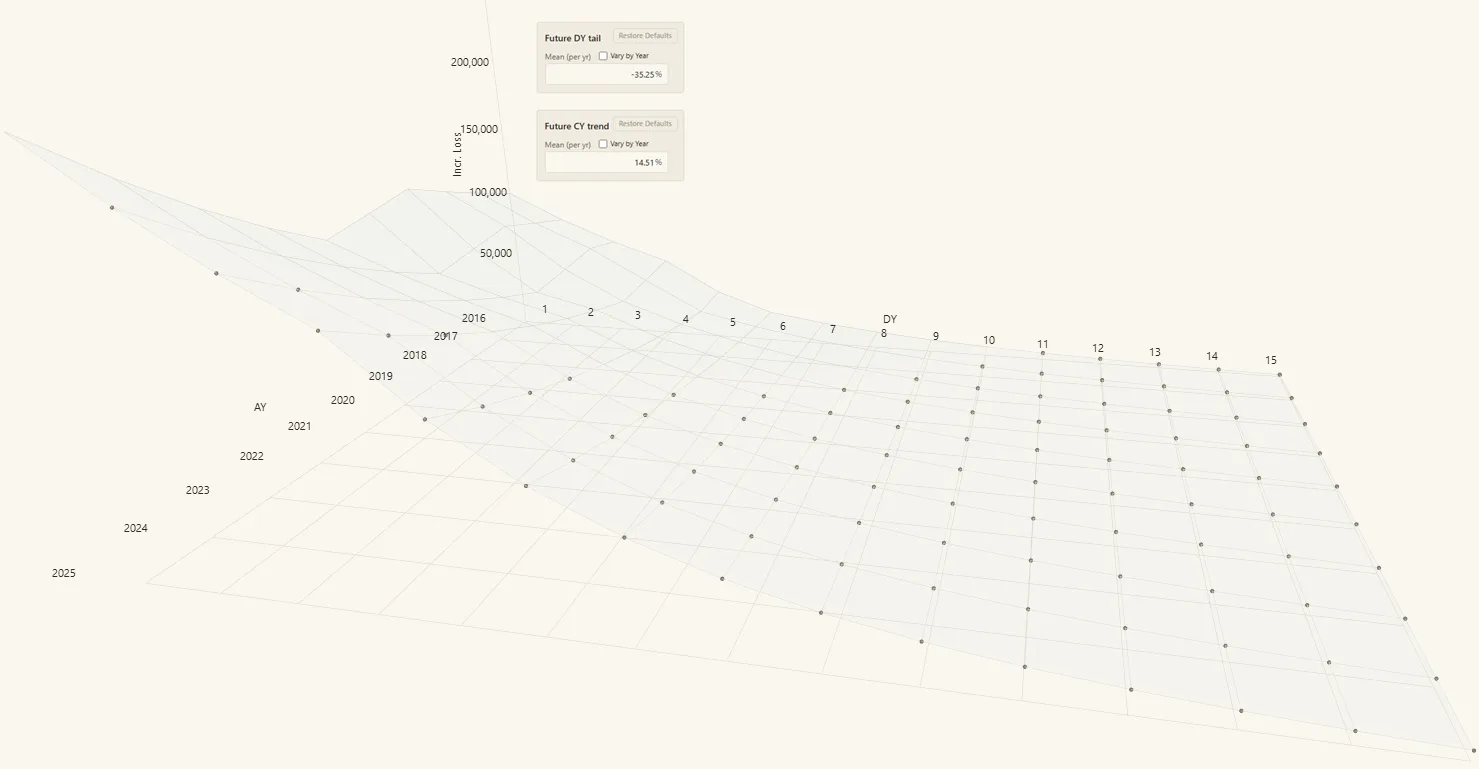
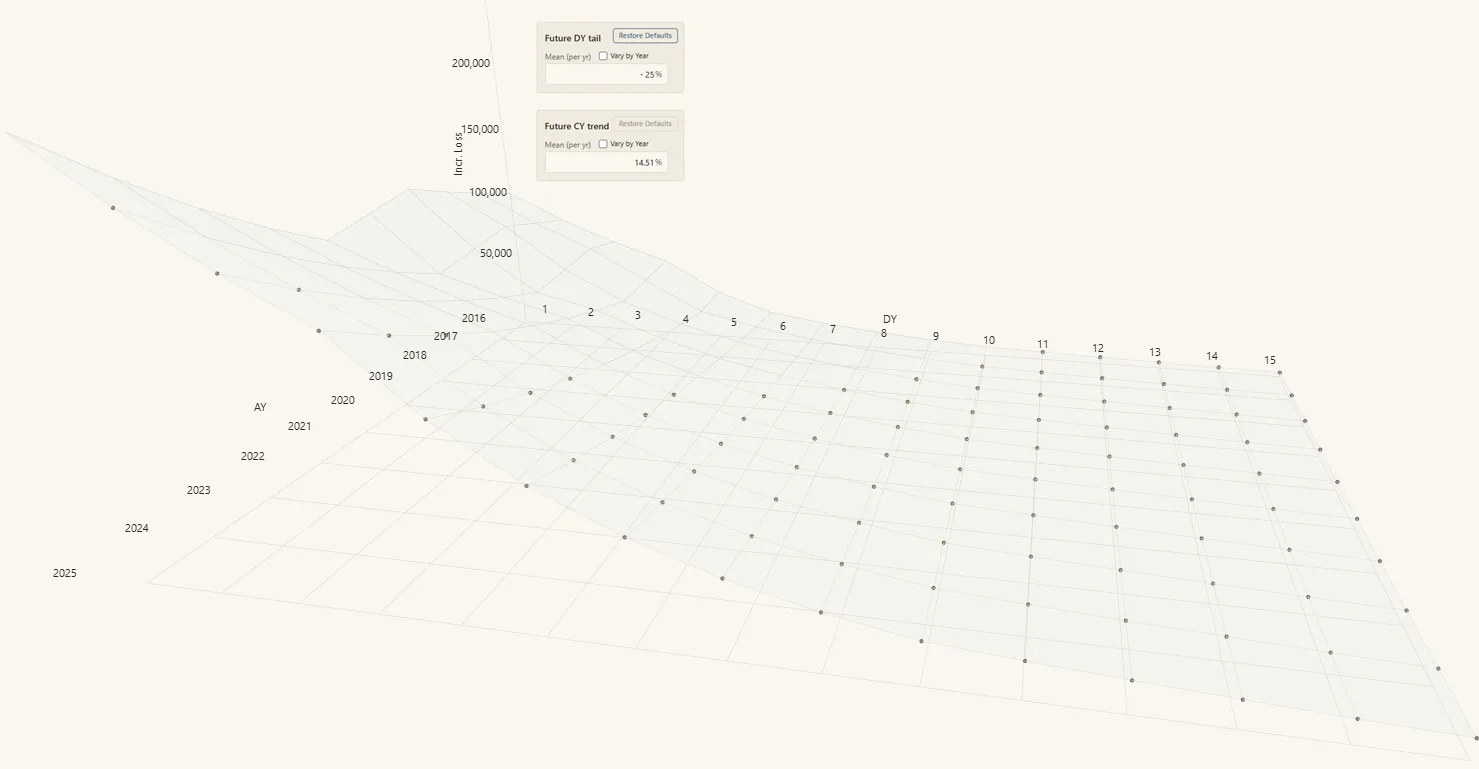
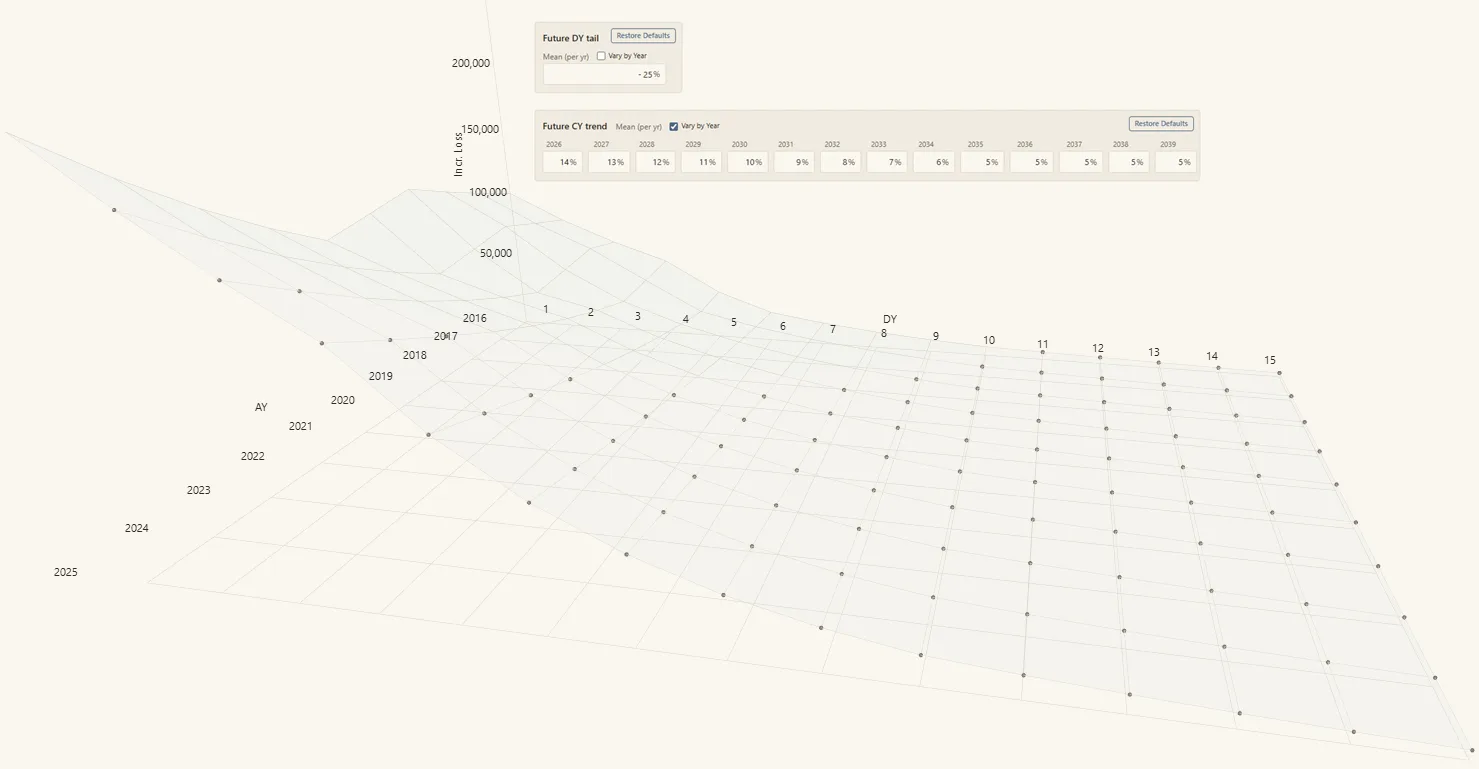
BASR's statistical modeling framework reflects the fact that the observed losses are just one outcome of a complex stochastic claim process, separating the trend structure (the signal) from random variation about it (the noise) while quantifying both process and parameter uncertainty in the projections. Deterministic methods do not reflect this and are over-parameterized, fitting both the signal and the noise in the data. Future calendar year trend and development year decay factor assumptions are fully customizable.
BASR produces the full predictive distribution of unpaid claims, by accident period and in total, with percentiles, reserve ranges, a one-year claims development result (CDR), and insights into historical trends, valuable not only to the reserving process but also to ratemaking, risk management, and capital modeling. The user can select the paid model, the reported model, or a combination of the two.
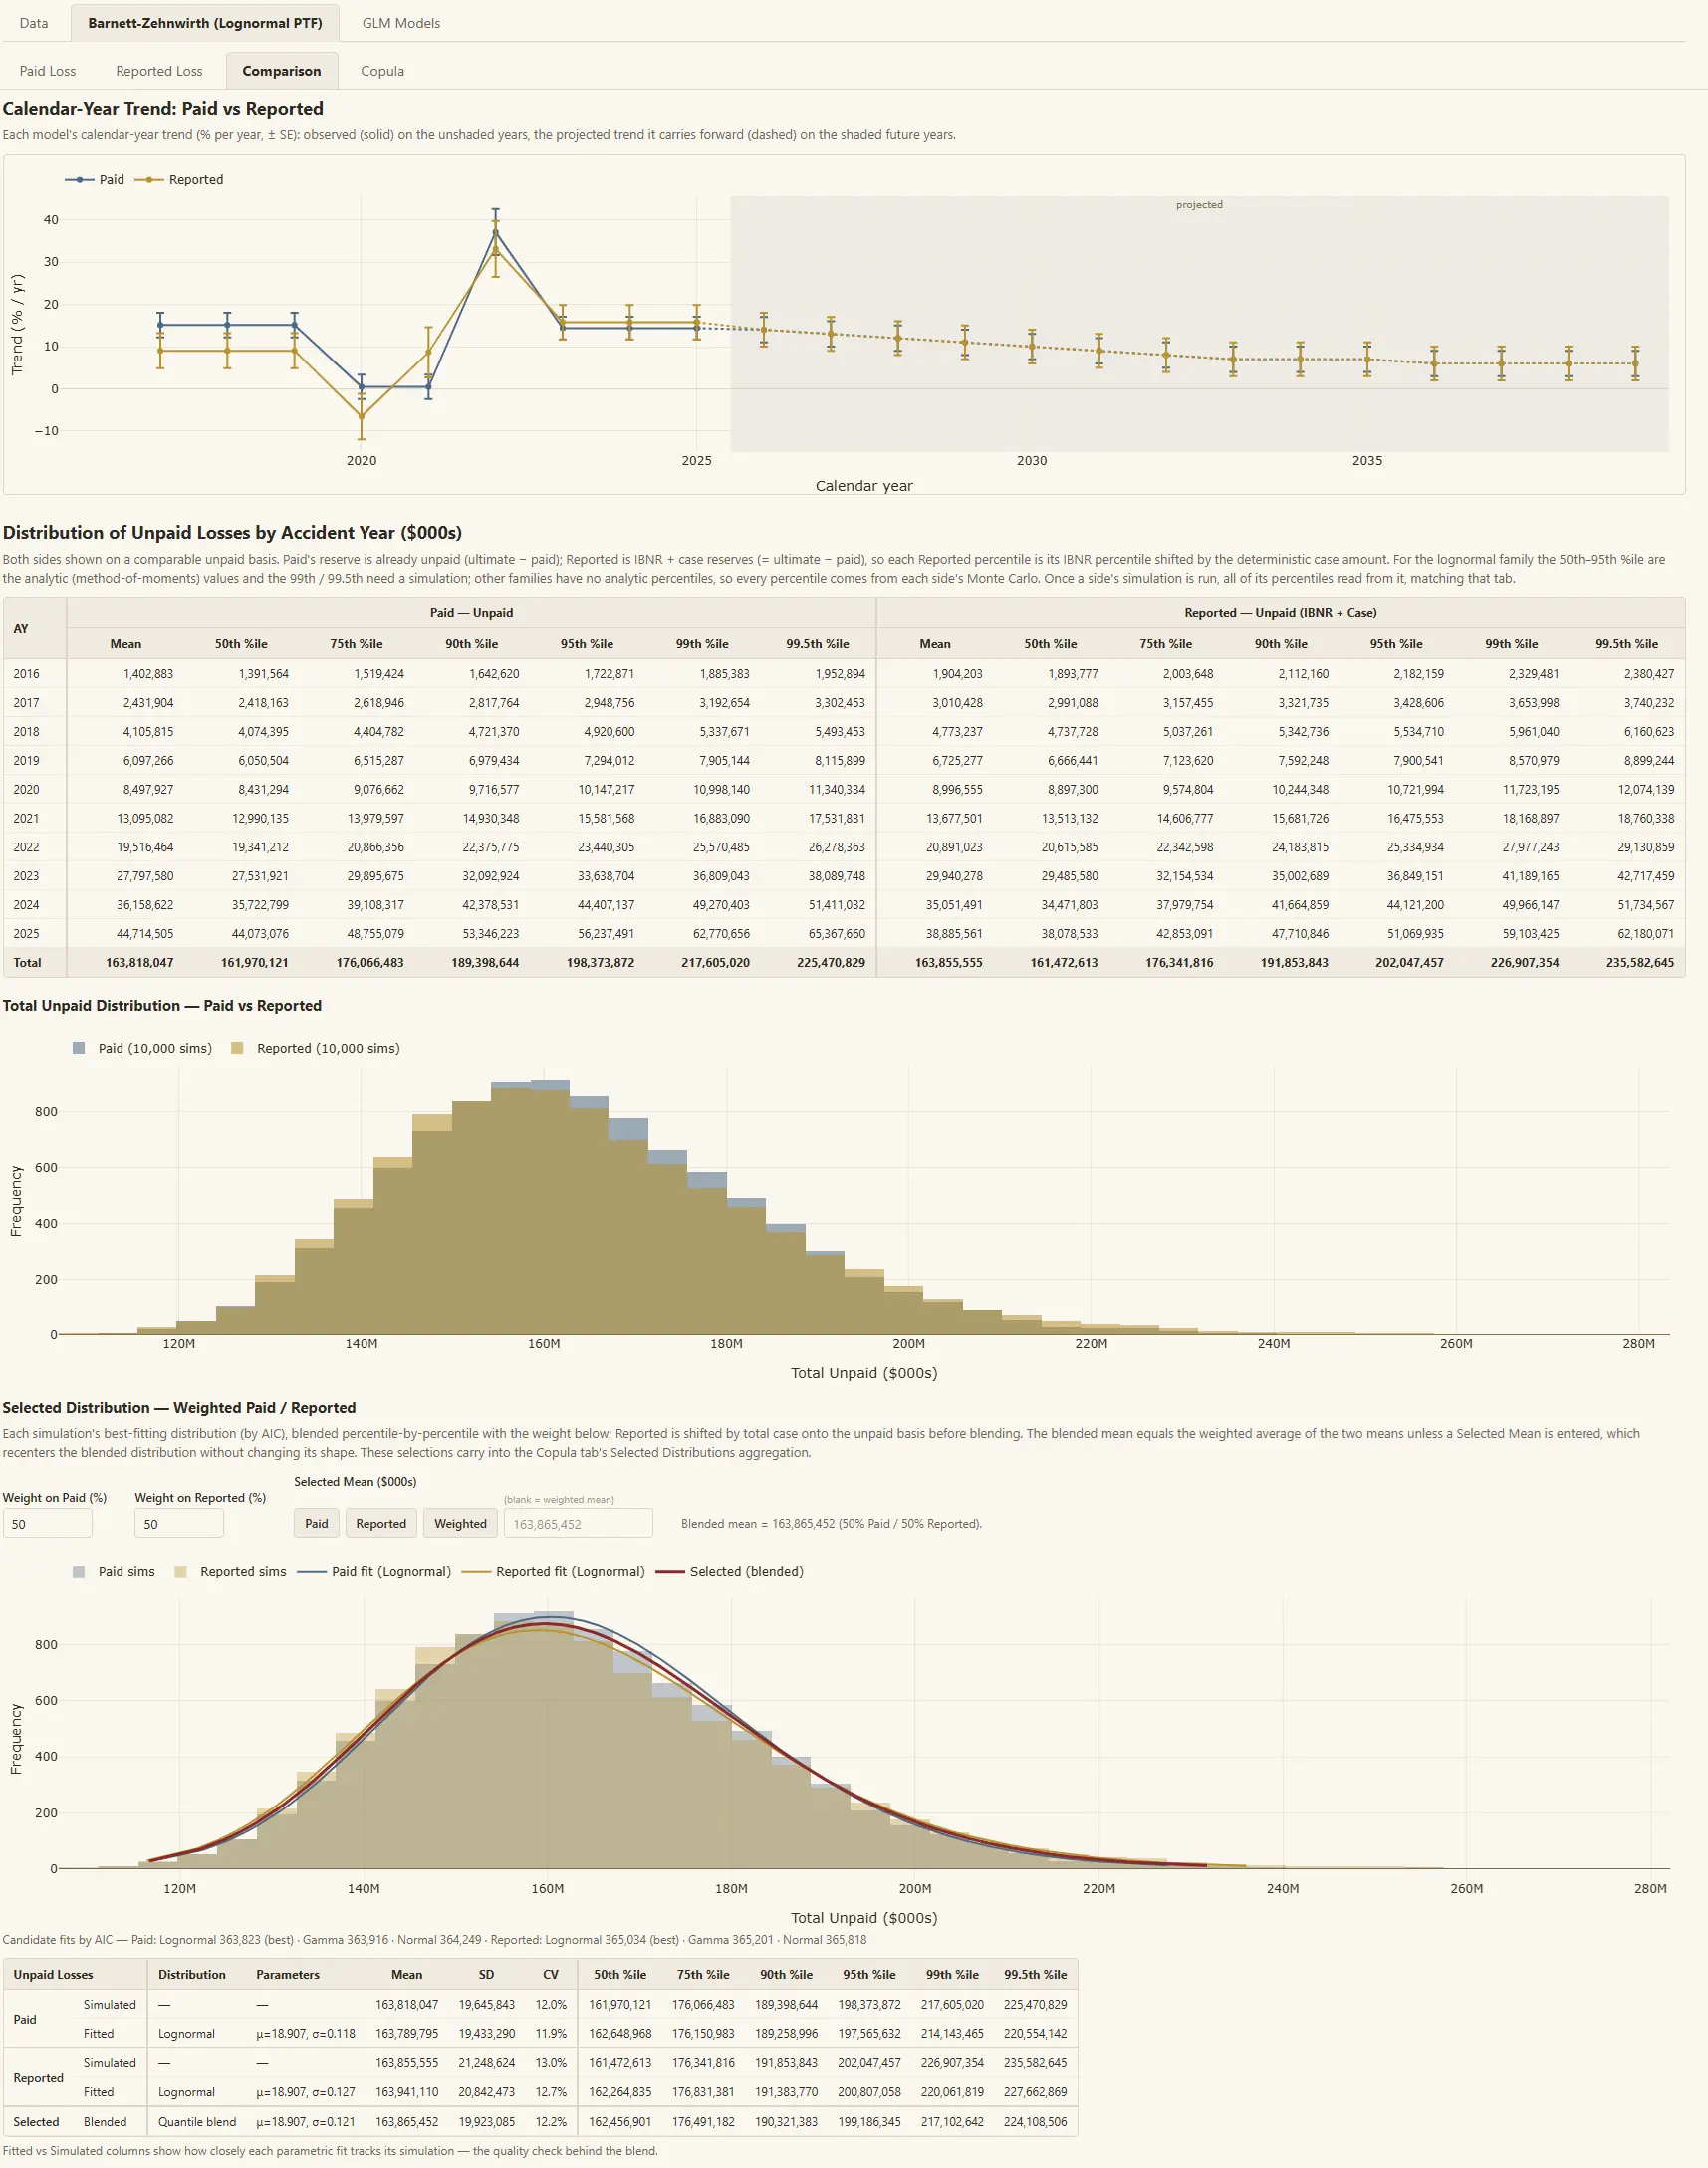
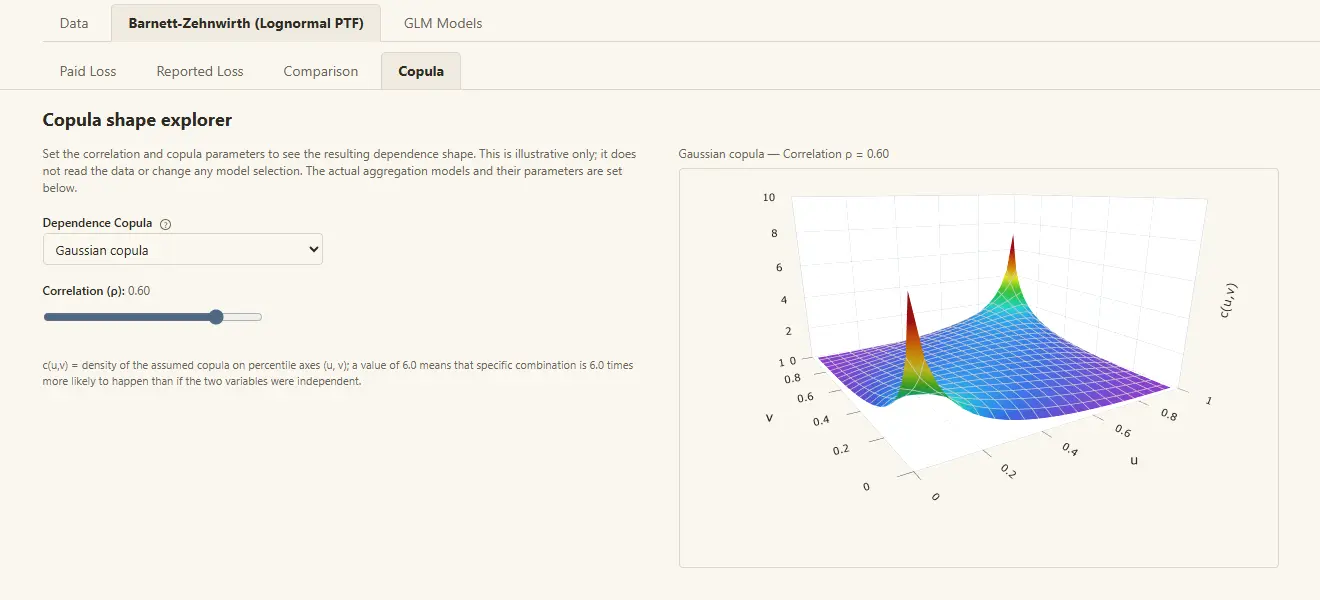
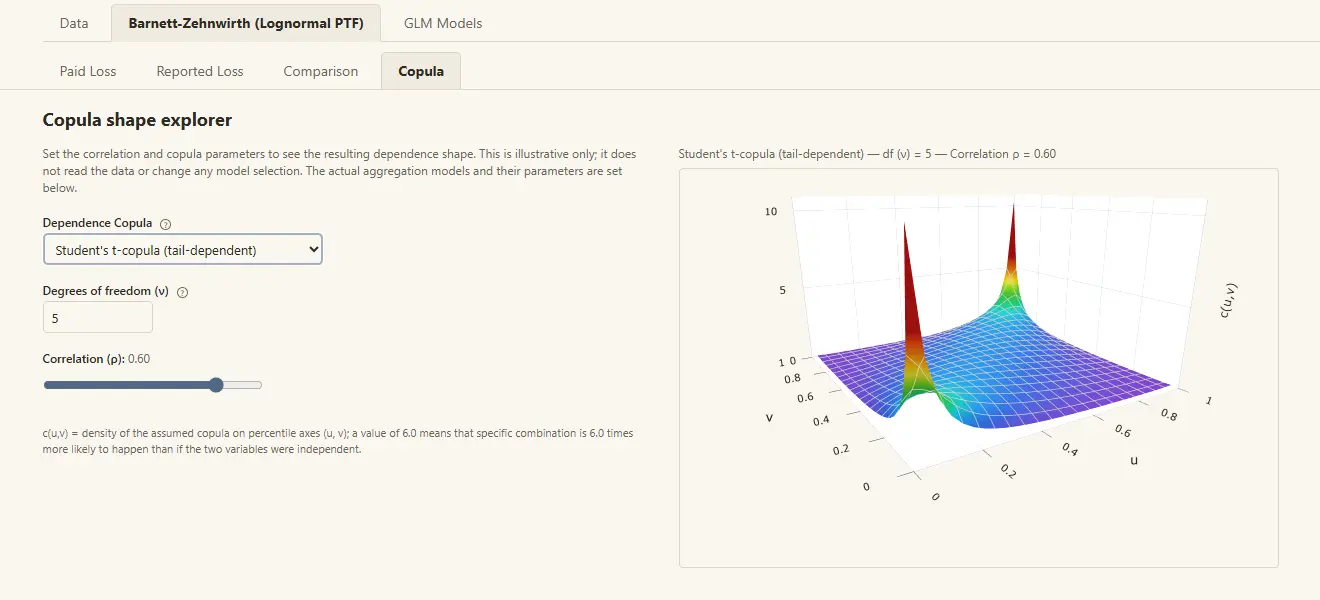
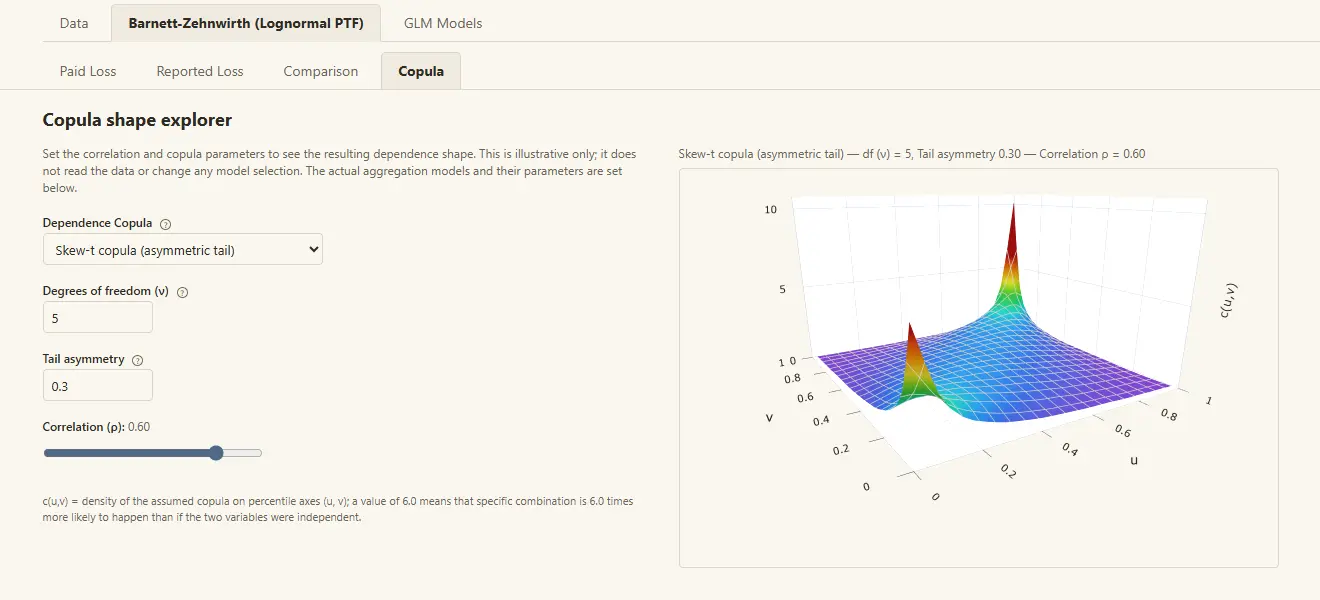
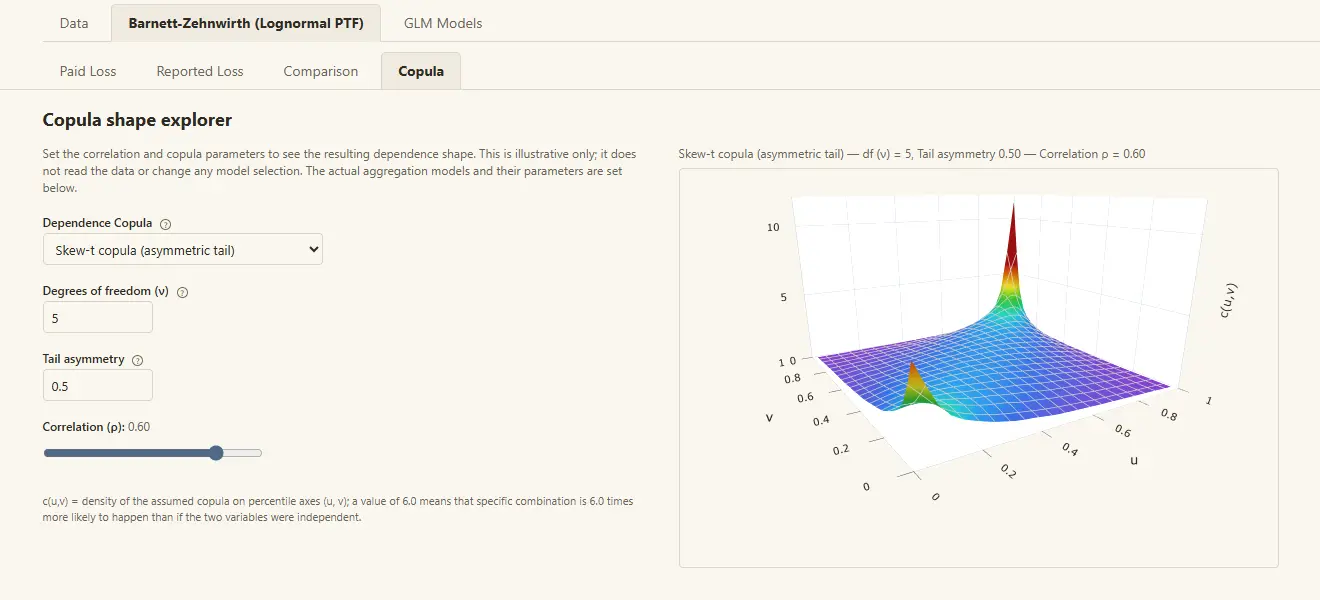
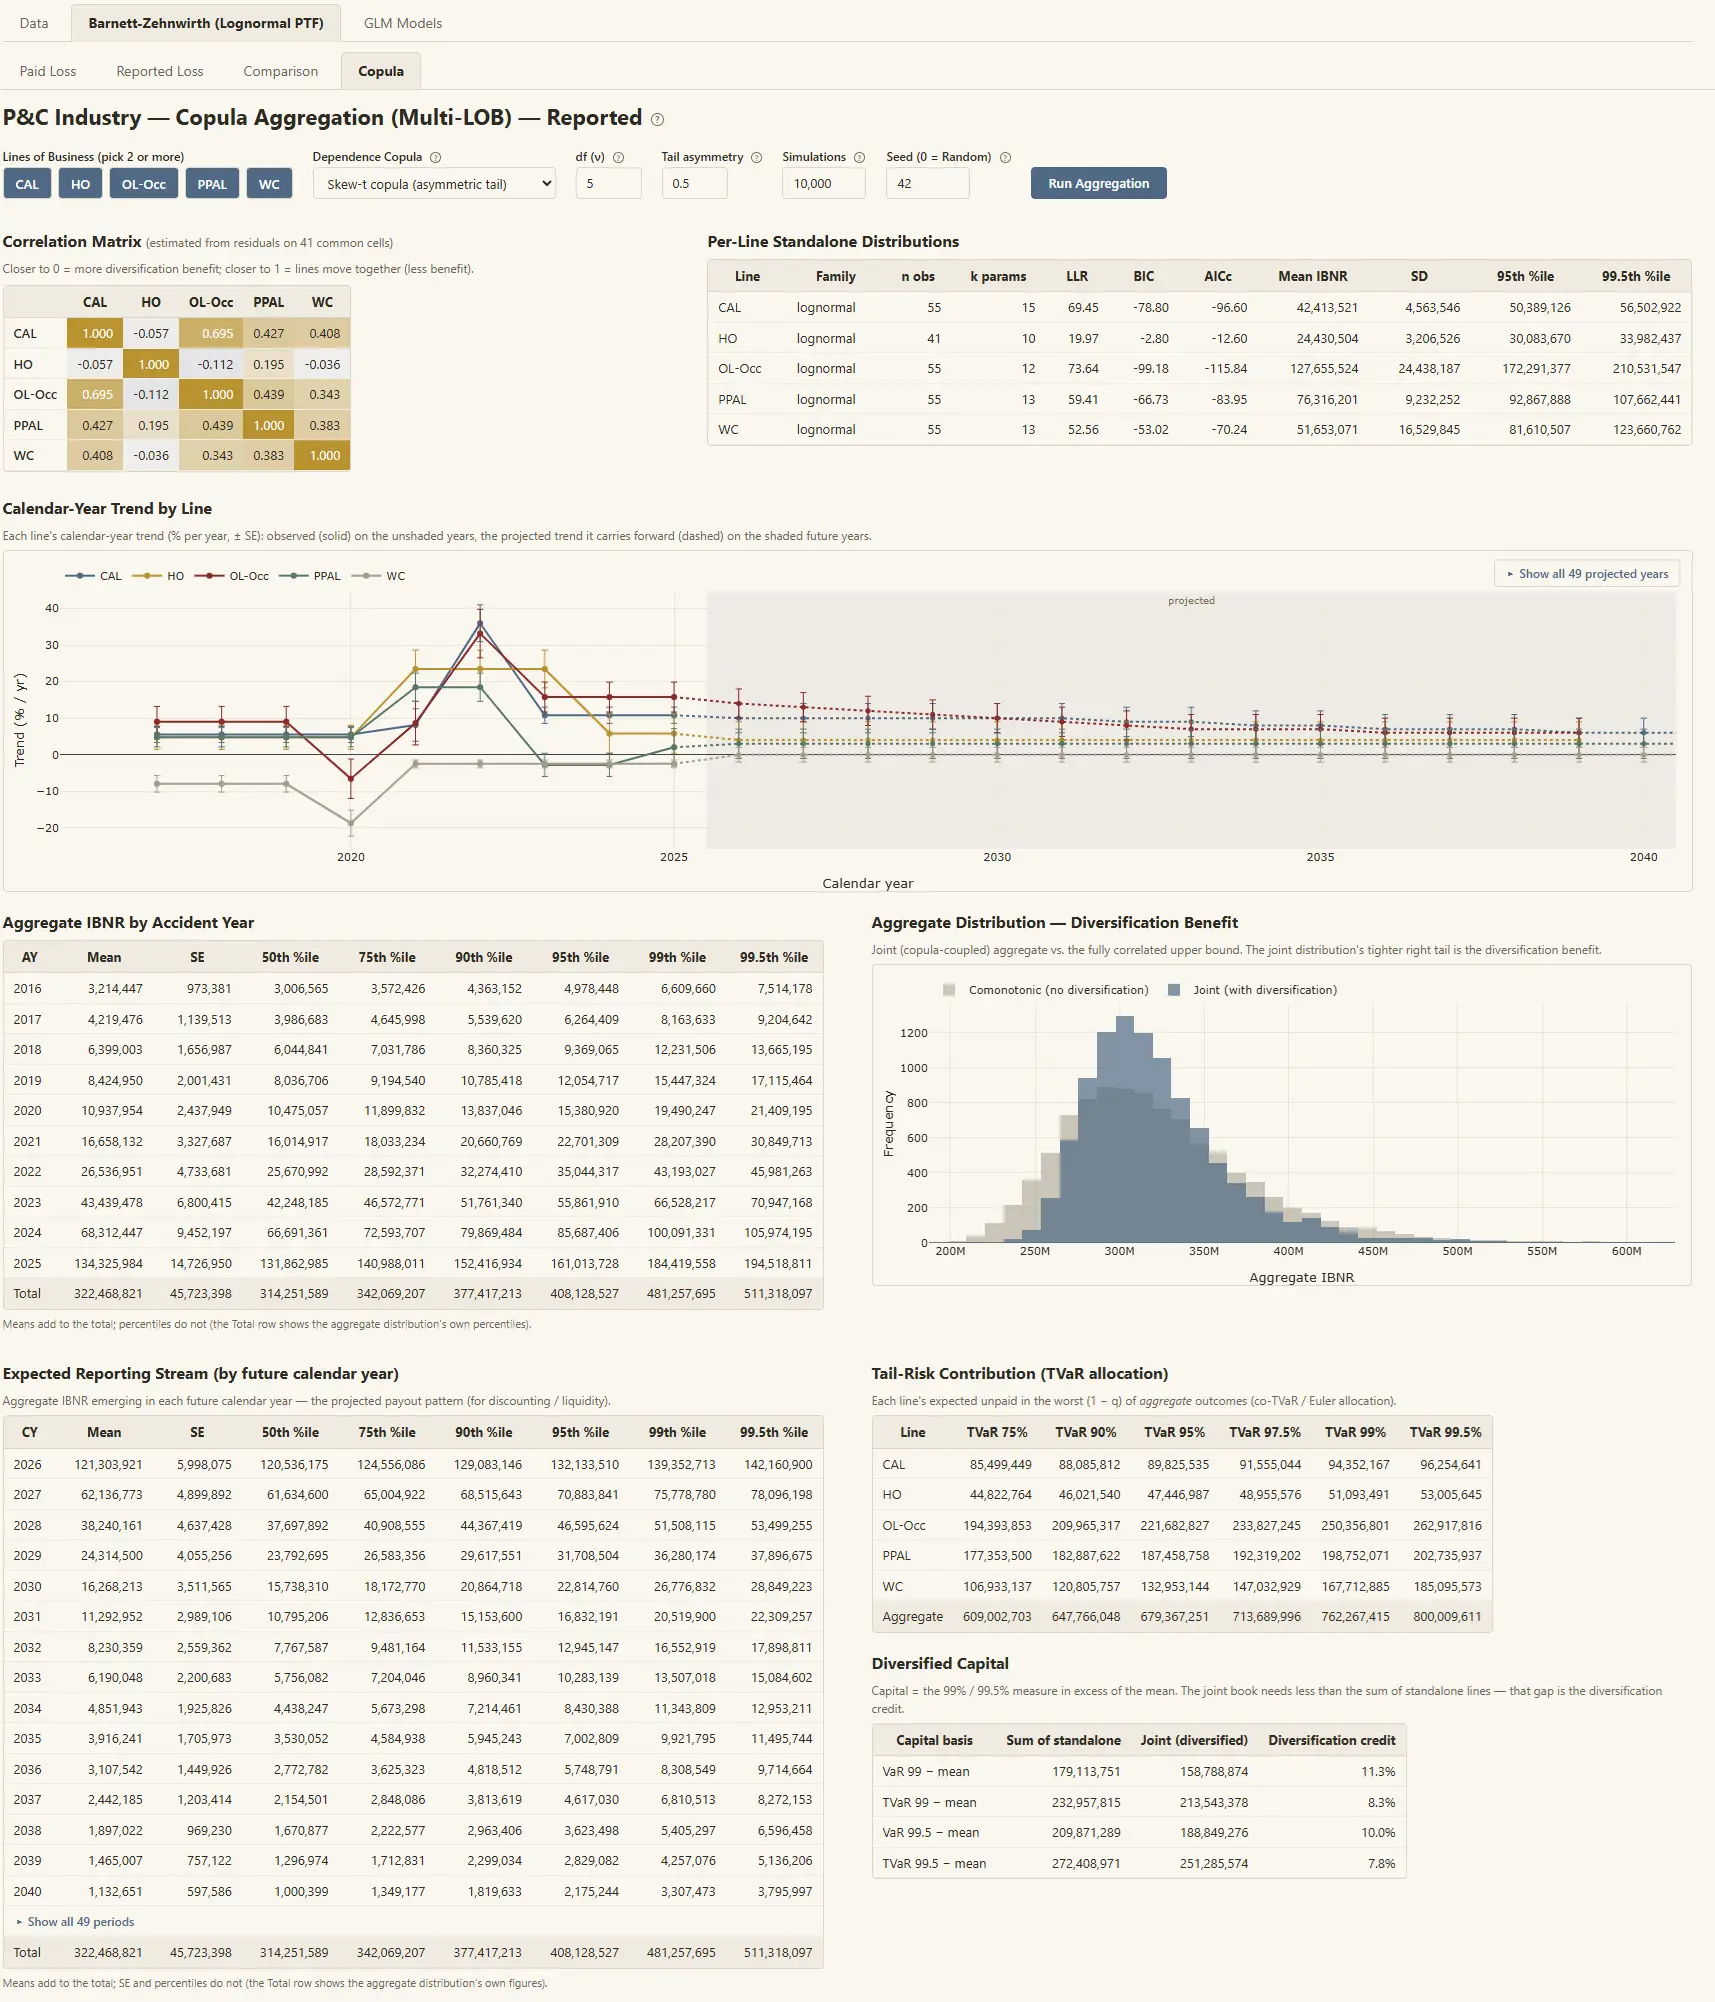
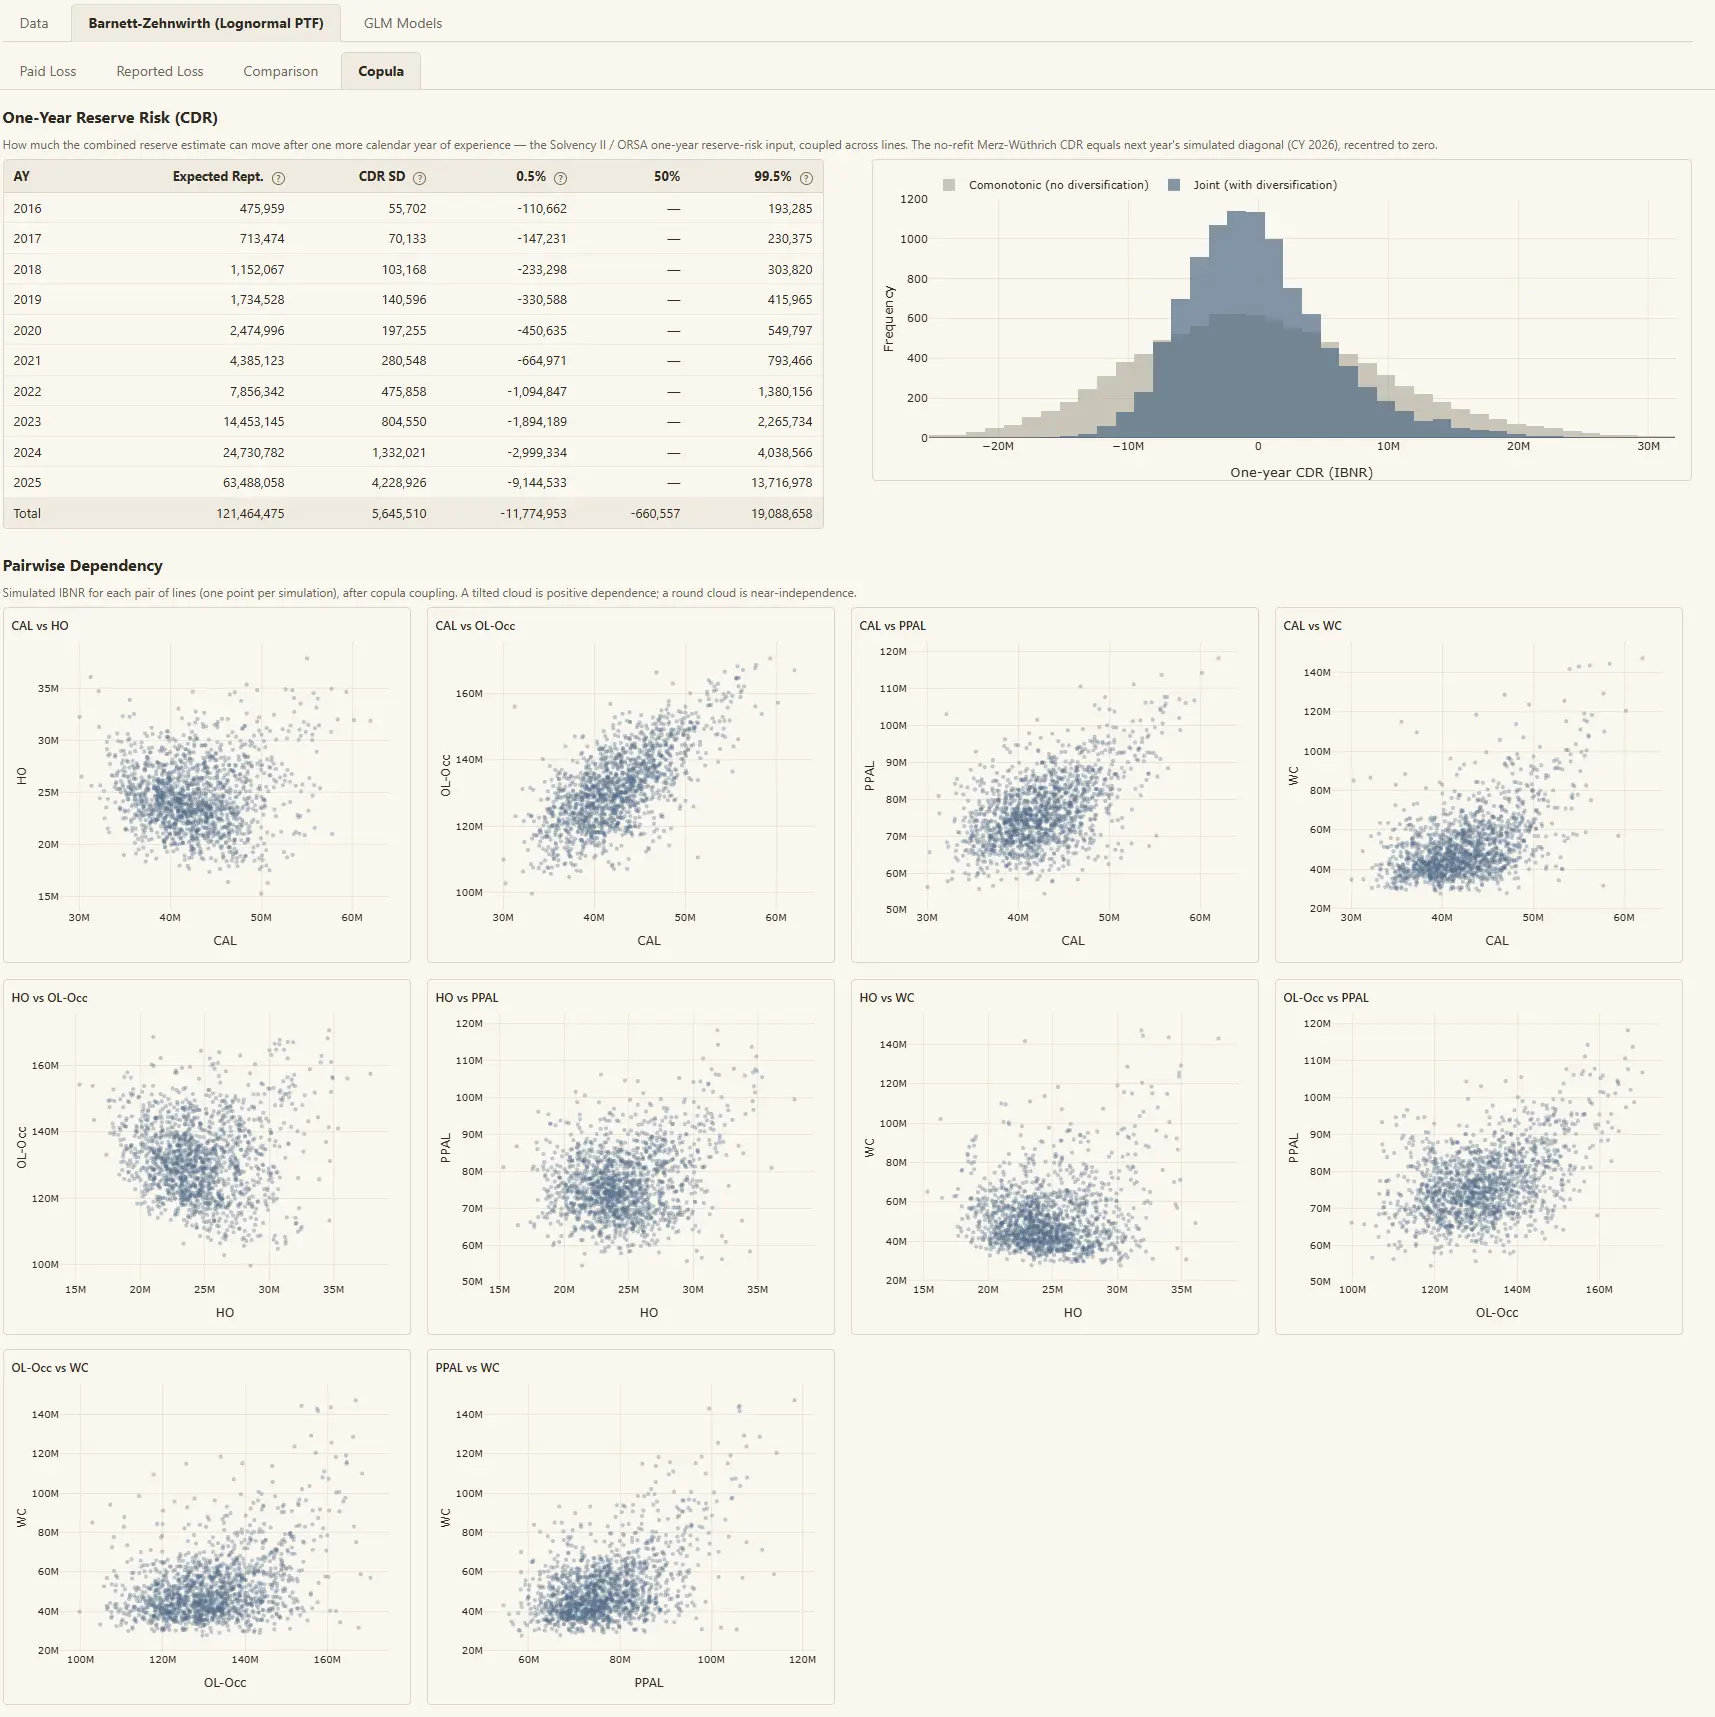
BASR can aggregate results across multiple lines of business or segments into an overall loss distribution by measuring correlations from the data and reflecting tail dependencies through customizable copula forms (including a visualizer to assist in modeling decisions). The resulting aggregate distribution will reflect diversification benefits and show the modeled dependencies between segments.
These loss models either use the log of incremental loss data (Lognormal PTF) or are defined only for positive values (GLM: Gamma and Inverse Gaussian), so zero and negative values cannot be fit. BASR retains the signal in the negative incremental values by rolling them back into the prior development period. Zeros are dropped from the model fit, so the resulting estimate is the expected value conditional on being greater than zero, which BASR can convert to an unconditional expectation using a zero-emergence adjustment.
BASR is now live for advisory engagements and commercial licensing. Schedule a meeting or send an email to begin a conversation.
A visual, step-by-step walkthrough of the statistical framework behind BASR, demonstrating how the methodology reflects the fact that the observed losses are just one outcome of a complex stochastic claim process, separating the signal from the noise, reducing overfitting, and providing more predictive estimates.
Read the Document
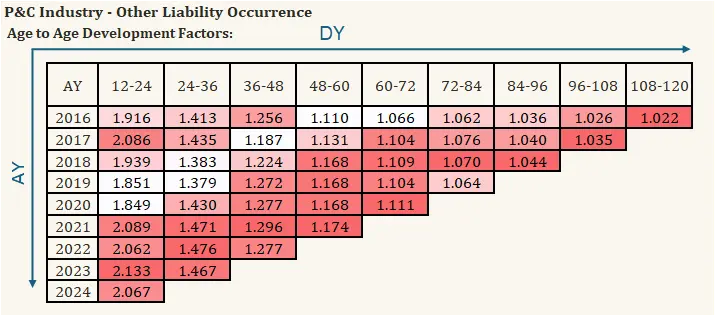
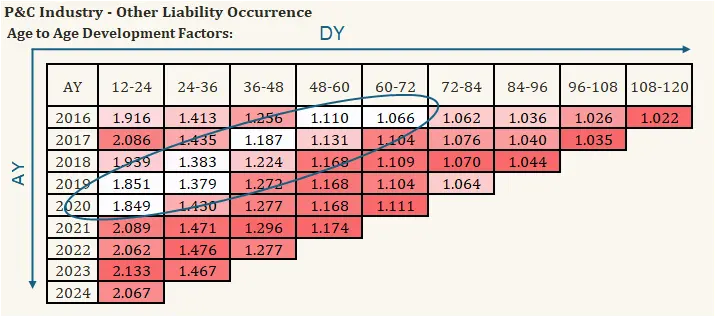
An example model build in the BASR software using 2025 Other Liability – Occurrence P&C industry Schedule P data.
Read the Document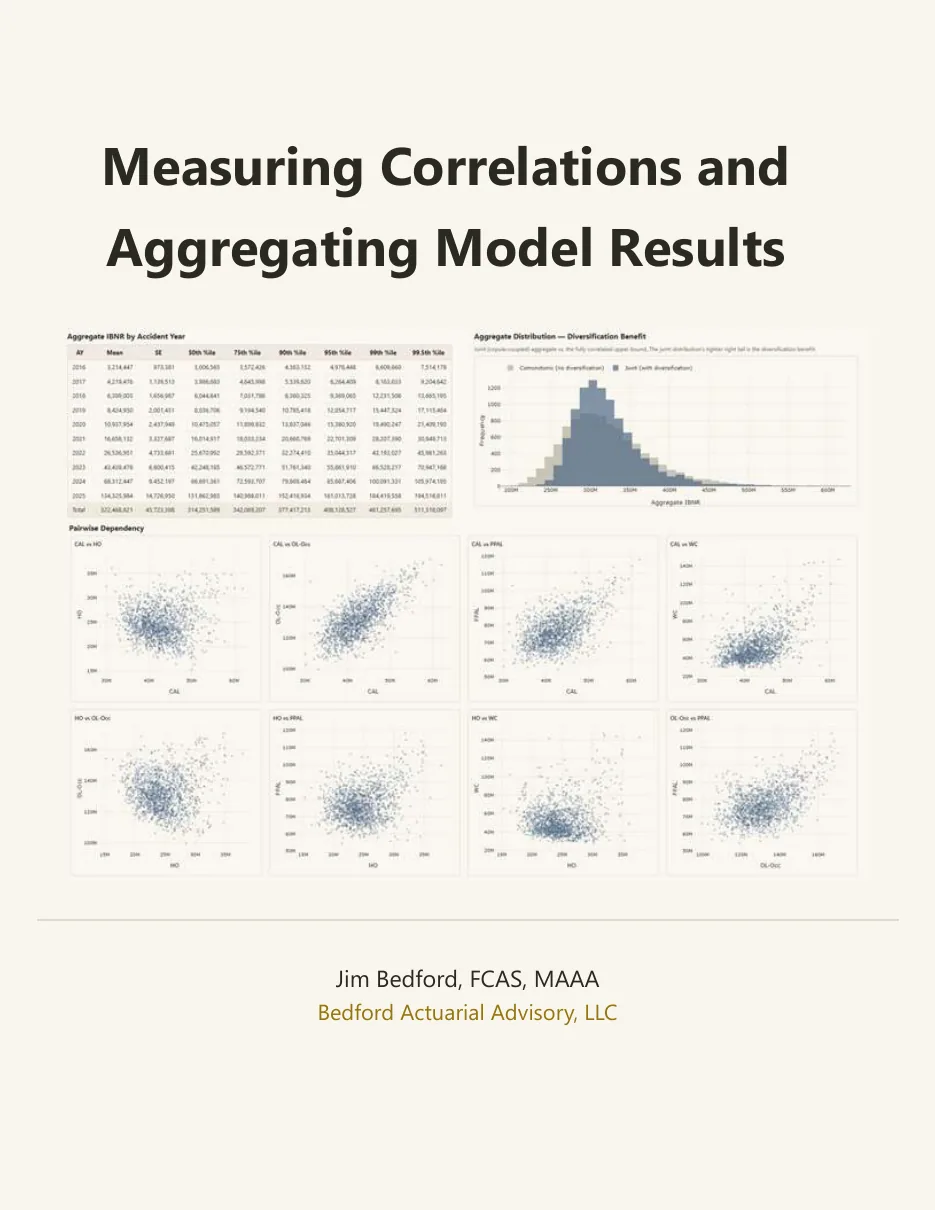
An illustration of how BASR measures correlations between segments in the data, allows users to select from customizable copula forms, and simulates aggregate distributions that reflect the diversification benefits and show the modeled dependencies between segments.
Read the Document